How We Work with Entrepreneurs and Business Owners
How We Work with Entrepreneurs and Business Owners Entrepreneurs and business owners represent a unique category of investors. Their approach to finance is fundamentally different from that of traditional clients. While many investors focus on market performance, benchmarks, and portfolio allocation models, entrepreneurs tend to think in terms of cash flow, operational risk, growth potential, and opportunity cost. This difference is not just philosophical—it has direct implications for how wealth should be structured, protected, and grown. At Income Capital Management, we do not apply a standard investment model to entrepreneurs. Instead, we adapt our strategies to reflect the realities they face every day: concentrated risk, irregular income, and long-term ambitions that extend beyond a single business cycle. Understanding the Entrepreneurial Mindset Entrepreneurs are used to making decisions under uncertainty. They build businesses, allocate resources, and manage risks in environments where outcomes are not guaranteed. Unlike traditional investors, they are not detached from risk—they live inside it. Their capital is often directly linked to the success of their business. Their income can fluctuate significantly. Their time horizon is shaped by business growth, exit strategies, or reinvestment cycles. Because of this, applying generic investment frameworks is ineffective. Wealth management for entrepreneurs must start with understanding their context. The Problem of Concentrated Risk One of the most common challenges faced by business owners is concentration risk. A significant portion of their wealth is typically tied to a single asset: their company. While this concentration may be the source of their success, it also represents a structural vulnerability. If the business faces operational difficulties, market disruptions, or economic downturns, both income and capital can be impacted simultaneously. This is why diversification outside the business is not optional—it is essential. Separating Personal Wealth from Business Exposure A key step in building a resilient financial structure is separating personal wealth from business risk. This separation allows entrepreneurs to: Protect part of their capital from business volatility Create independent income streams Reduce overall financial risk In practice, this means allocating capital into diversified investment strategies that are not directly correlated with the business itself. This could include exposure to financial markets, real assets, and alternative investments. Managing Irregular Income Unlike salaried professionals, entrepreneurs rarely benefit from predictable income. Revenue can vary significantly depending on business performance, market conditions, or reinvestment decisions. This irregularity creates additional complexity in financial planning. Liquidity management becomes a critical component of the overall strategy. We work with clients to ensure that sufficient liquidity is always available to: Cover personal and family needs Support business opportunities when required Avoid forced liquidation of investments This balance between invested capital and available liquidity is essential for maintaining flexibility. Designing Long-Term Investment Strategies Entrepreneurs are naturally oriented toward long-term value creation. They build businesses over years, sometimes decades. Their investment strategy should reflect the same horizon. At Income Capital Management, we design portfolios that: Survive multiple economic cycles Provide diversification across asset classes Balance growth, income and protection This typically involves combining different investment engines such as: Global growth strategies for capital appreciation Real estate investments for income stability Forex strategies for diversification Gold or real assets for protection Each component plays a specific role within the broader portfolio structure. The Portfolio as a Stabiliser For entrepreneurs, the business is often the engine of wealth creation. However, relying entirely on this engine creates vulnerability. The investment portfolio should act as a stabiliser. Its role is not to replicate the business, but to complement it. This means providing: Stability during periods of business volatility Diversification across different economic drivers Liquidity when needed A well-structured portfolio reduces dependence on a single source of wealth. Adapting to Business Cycles Every business operates within cycles. Periods of growth are followed by consolidation, and sometimes by downturns. Investment strategies must be designed to adapt to these cycles. During expansion phases, entrepreneurs may choose to allocate more capital to their business. During uncertain periods, preserving liquidity and protecting capital may become the priority. Our advisory process is built to adjust dynamically to these changing conditions. A Client-Centric Approach No two entrepreneurs are the same. Each client has different objectives, risk tolerance, and financial structures. For this reason, we do not apply predefined solutions. We build tailored strategies based on: The structure of the business The level of risk concentration The liquidity needs The long-term objectives This ensures that the investment strategy is aligned with the client’s overall financial reality. Beyond Investment: Strategic Advisory Working with entrepreneurs often goes beyond portfolio construction. It involves strategic discussions around: Timing of liquidity events Capital allocation between business and investments Risk management across different assets In this context, the role of the advisor is not limited to recommending investments. It becomes a strategic partnership. Conclusion Entrepreneurs build value through their businesses. However, long-term wealth requires a broader perspective. Separating personal wealth from business risk, managing liquidity, and building diversified portfolios are essential steps in this process. At Income Capital Management, we help entrepreneurs translate their business success into structured and resilient financial strategies. Because in the long run, it is not just about building a company. It is about building sustainable wealth beyond it. LinkedIn Post: View original post
Why Cash Is a Strategy, Not a Failure
Why Cash Is a Strategy, Not a Failure In financial markets, there is a widespread belief that capital must always be fully invested. Cash, in this narrative, is often perceived as idle, inefficient, or even a sign of indecision. Investors are frequently told that money sitting on the sidelines is “not working,” and that every available euro or dollar should be deployed into the market to maximize returns. This perspective, however, reflects a simplified understanding of portfolio management. In reality, cash is not inactivity. It is strategy. When used correctly, cash becomes one of the most powerful and flexible tools available to investors. It provides optionality, stability, and control—qualities that are often undervalued during bullish markets but become essential during periods of uncertainty. The Misconception About Cash The misconception around cash stems from the way performance is typically measured. Returns are often evaluated relative to fully invested benchmarks. When markets are rising, holding cash can feel like underperformance. This creates psychological pressure. Investors begin to associate cash with missed opportunities rather than with risk management. However, this view ignores the broader objective of investing: not just maximizing returns, but preserving capital and managing risk over time. Cash plays a different role compared to equities, bonds, or real assets. It is not designed to generate high returns. It is designed to provide stability and flexibility within the overall portfolio. Liquidity as a Strategic Asset Liquidity is one of the most valuable characteristics in financial markets. Cash provides immediate access to capital without the need to liquidate other assets. This creates several advantages: Flexibility: the ability to adjust portfolio allocation quickly Optionality: the capacity to act when opportunities arise Protection: the avoidance of forced selling during downturns In stable market conditions, these benefits may seem secondary. In volatile environments, they become critical. Avoiding Forced Decisions One of the greatest risks in investing is not volatility itself, but the inability to manage it properly. Investors without sufficient liquidity may be forced to make decisions under pressure. This often results in selling assets during unfavorable conditions, locking in losses and disrupting long-term strategies. Cash eliminates this constraint. It allows investors to remain patient, to avoid reacting impulsively, and to maintain control over their decisions. In this sense, cash is not just a financial asset—it is a psychological stabilizer. Optionality and Opportunity Markets are not linear. Periods of stability are often followed by sudden dislocations, corrections, or shifts in sentiment. These moments, while uncomfortable, often create the best investment opportunities. However, only investors with available capital can take advantage of them. Cash provides this optionality. It allows investors to deploy capital when valuations become attractive, rather than being fully exposed at all times. In this way, liquidity becomes a source of strategic advantage. The Timing Advantage of Cash While it is impossible to perfectly time markets, having cash enables better timing decisions. Investors with liquidity can: Enter positions gradually rather than all at once Take advantage of market corrections Rebalance portfolios efficiently This does not mean attempting to predict short-term movements. It means being prepared to act when conditions change. How Much Cash Is Enough? There is no universal answer to how much cash a portfolio should hold. The appropriate allocation depends on multiple factors: Market conditions and volatility levels Investor risk tolerance Time horizon and investment objectives Structure of the overall portfolio For example, in highly volatile environments, a higher level of liquidity may be justified. In more stable conditions, cash allocation may be reduced. The key is intentional allocation. Cash should not be the result of indecision. It should be a deliberate component of the investment strategy. Cash in a Multi-Asset Portfolio Within a diversified portfolio, each asset class has a specific role. Equities provide growth Real estate generates income Gold offers protection Forex strategies add diversification Cash provides liquidity and flexibility When combined effectively, these elements create a balanced structure capable of navigating different market environments. Cash, in this context, acts as a stabilizer. It reduces overall volatility and enhances the portfolio’s ability to adapt. The Psychological Dimension of Cash Investing is not purely analytical. It is also behavioral. Emotions play a significant role in decision-making, particularly during periods of market stress. Holding an appropriate level of cash can reduce anxiety and improve discipline. Investors who feel secure in their liquidity position are less likely to panic during downturns and more likely to follow their long-term strategy. This behavioral advantage is often underestimated, yet it can have a significant impact on outcomes. Cash and Strategic Patience One of the most important qualities in investing is patience. Markets reward disciplined investors over time, but only those who are able to remain consistent through different cycles. Cash supports this patience. It allows investors to wait for the right opportunities rather than feeling compelled to act constantly. In a world driven by constant information and rapid decision-making, this ability to pause is a competitive advantage. Conclusion Cash should not be viewed as an absence of strategy or a sign of hesitation. It is a deliberate choice within a broader investment framework. By providing liquidity, optionality, and protection, cash enhances the resilience of a portfolio and supports more effective decision-making. In complex and unpredictable markets, these qualities are not secondary. They are essential. Understanding the role of cash transforms it from a perceived weakness into a strategic strength. LinkedIn Post: Read the original post
Global Growth Fund: Turning Trends into Long-Term Value
Global Growth Fund: Turning Trends into Long-Term Value Growth investing today is often misunderstood. Many associate it with chasing fast-moving trends, speculative sectors, or short-term momentum. In reality, sustainable growth investing requires discipline, patience, and a structured approach. At Income Capital Management, our Global Growth strategy is not about following hype. It is about identifying structural trends and translating them into long-term value creation. Beyond Hype: What Growth Really Means Markets are constantly influenced by innovation, disruption, and global competition. However, not all growth is sustainable. We focus on companies that demonstrate: Strong balance sheets Clear and scalable business models Long-term competitive advantages Resilience across economic cycles This approach filters out noise and isolates real value. The Role of Secular Trends Secular trends are long-term structural changes that reshape industries. Examples include digitalization, energy transition, and global demographic shifts. Investing in these trends requires patience. The objective is not to capture short-term spikes, but to participate in long-term transformations. Discipline in Valuation Growth without valuation discipline leads to risk. Many investors overpay for growth, assuming that momentum will continue indefinitely. Our approach integrates valuation analysis to ensure that growth potential is supported by realistic pricing. Integration Within a Multi-Asset Strategy The Global Growth Fund is not standalone. It is part of a broader portfolio including: Forex strategies Real estate investments Physical gold High yield instruments This diversification allows clients to capture growth while maintaining stability. Conclusion Growth investing is not about speed. It is about direction. With the right framework, innovation becomes opportunity, and long-term value becomes achievable. LinkedIn Post: View original post
How I Use Scenarios to Stress-Test Client Portfolios
How I Use Scenarios to Stress-Test Client Portfolios One of the most common assumptions in investing is that the future can be predicted. Investors often rely on forecasts, expert opinions, and market expectations to guide their decisions. However, financial markets are inherently uncertain. Economic cycles shift, geopolitical tensions emerge unexpectedly, and policy decisions can rapidly alter the investment landscape. For this reason, professional portfolio management does not rely on prediction. It relies on preparation. At Income Capital Management, we approach portfolio construction with a clear principle: we do not try to guess the future, we prepare for multiple possible futures. Why Prediction Is Not Enough Traditional investment approaches often depend heavily on forecasts. Analysts predict interest rates, economic growth, inflation trends, and market direction. While these forecasts can provide useful context, they are inherently limited. Markets are influenced by variables that cannot be fully anticipated. Unexpected events—such as geopolitical conflicts, sudden policy shifts, or financial crises—can disrupt even the most well-reasoned predictions. Relying exclusively on a single expected scenario creates vulnerability. If that scenario does not materialize, portfolios can become exposed to significant losses. This is why scenario analysis plays a critical role in modern investment strategy. From Prediction to Preparation Scenario analysis shifts the focus from forecasting a single outcome to evaluating multiple potential environments. Instead of asking, “What will happen?”, the question becomes: “What happens to the portfolio if different things happen?” This approach transforms uncertainty from a threat into a manageable variable. By understanding how a portfolio behaves under different conditions, investors gain clarity, confidence, and control over their financial decisions. The Core Scenarios We Analyze In our portfolio stress-testing process, we model several macroeconomic environments that historically have had a significant impact on financial markets. These scenarios include: Sudden interest rate increases Economic recession or slowdown Inflation shocks Geopolitical instability Liquidity tightening in global markets Each of these environments affects asset classes in different ways. Understanding these relationships is essential for building resilient portfolios. Interest Rate Shock Scenario Interest rates are one of the most powerful drivers of financial markets. A sudden increase in rates can impact equities, bonds, currencies, and real assets simultaneously. In this scenario, we evaluate: Sensitivity of bond and credit exposure Impact on equity valuations Currency adjustments in Forex strategies Real estate financing conditions By modeling these effects, we can identify vulnerabilities and adjust allocations accordingly. Recession Scenario Economic slowdowns or recessions affect corporate earnings, employment levels, and investor sentiment. In a recession scenario, we assess: Equity market drawdown exposure Credit risk in high-yield instruments Liquidity availability Defensive asset allocation effectiveness The goal is to ensure that portfolios maintain stability even in periods of economic contraction. Geopolitical Shock Scenario Geopolitical events—such as conflicts, trade disruptions, or political instability—can introduce sudden volatility into global markets. These events often impact: Currency markets (Forex) Commodity prices Safe-haven assets such as gold Global equity sentiment Scenario analysis allows us to evaluate how portfolios respond to these shocks and whether hedging strategies are sufficient. Inflation and Liquidity Scenarios Inflation dynamics and liquidity conditions are closely linked to central bank policy decisions. These variables influence asset pricing across the entire financial system. We test portfolios against scenarios such as: Persistently high inflation Rapid disinflation Liquidity tightening Expansionary monetary policy Each of these conditions requires different portfolio positioning. Asset Class Behavior Under Stress A key benefit of scenario analysis is understanding how different asset classes behave under stress conditions. For example: Forex strategies may benefit from currency volatility Real estate may provide stability but face financing pressure Equities may experience drawdowns during risk-off periods Gold often acts as a hedge during uncertainty By combining these assets within a diversified framework, portfolios can balance risk and return across different environments. From Analysis to Action Scenario analysis is not just an academic exercise. It directly informs portfolio decisions. Based on the results of stress testing, we may: Rebalance asset allocation Reduce exposure to vulnerable sectors Increase defensive positioning Adjust currency exposure Enhance diversification across asset classes These adjustments are made proactively, rather than reactively. Building Portfolio Resilience Resilience is the ability of a portfolio to withstand shocks while maintaining long-term growth potential. A resilient portfolio does not aim to avoid all volatility. Instead, it is designed to absorb shocks without compromising its long-term trajectory. Scenario analysis plays a central role in achieving this objective. The Psychological Advantage of Stress Testing Beyond technical benefits, scenario analysis provides an important psychological advantage for investors. When clients understand how their portfolio is expected to behave under stress, they are less likely to react emotionally during market turbulence. Confidence comes from preparation. Instead of reacting impulsively to market events, investors can rely on a structured framework that has already considered potential risks. Preparing for Multiple Futures The future will never unfold exactly as expected. Markets will continue to surprise, and new risks will emerge over time. However, by preparing for multiple scenarios, investors can reduce uncertainty and improve decision-making. This approach allows portfolios to remain flexible while maintaining strategic direction. Conclusion Successful investing is not about predicting the future with certainty. It is about building portfolios that can adapt to different outcomes. Scenario analysis transforms uncertainty into a structured process, allowing investors to evaluate risks, adjust exposure, and maintain confidence in their strategy. When you understand how your portfolio behaves under stress, you are better equipped to stay the course—or to adjust with purpose. And in complex financial markets, that clarity makes all the difference. LinkedIn Post:Read the original discussion on LinkedIn
24 Months Journey: Building an Independent Asset Management Platform
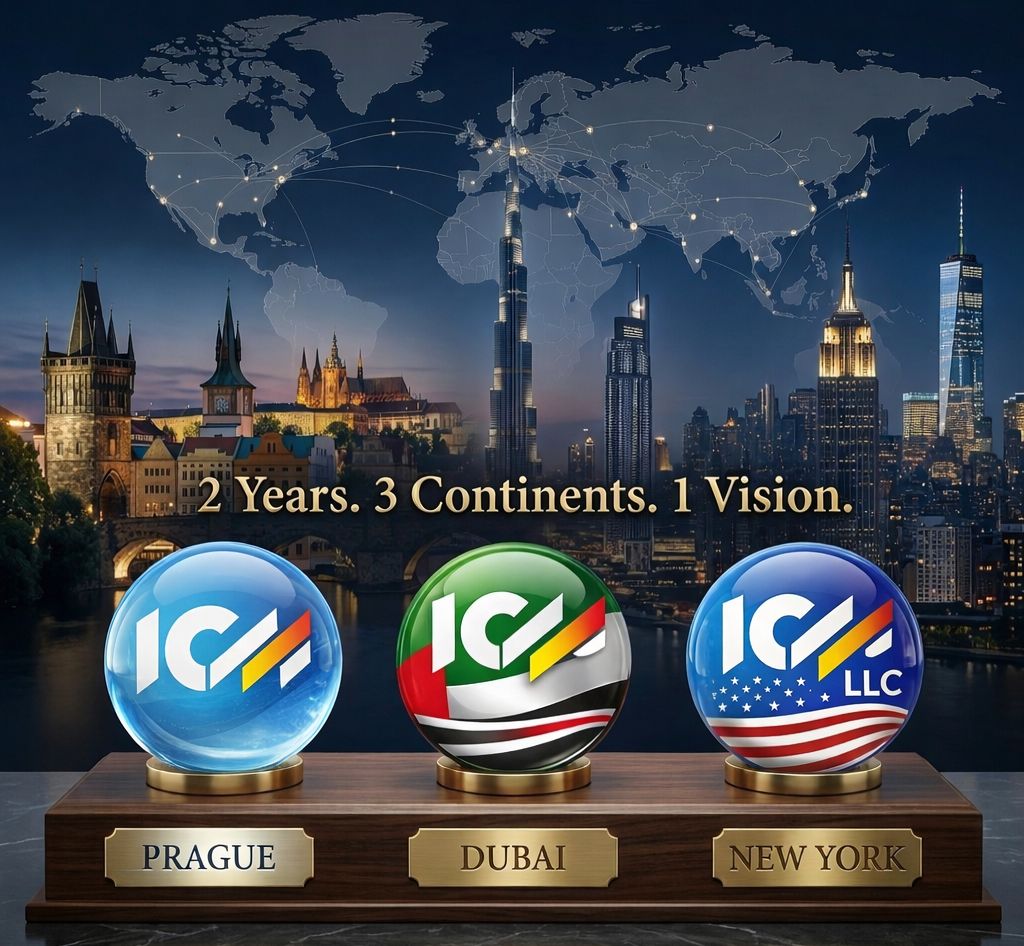
24 Months Journey: Building an Independent Asset Management Platform In the world of finance, two years can feel like a very short period of time. Markets move quickly, opportunities evolve, and competition is constant. Yet, when a project is built with clarity, discipline and long-term vision, even a relatively short timeframe can represent a meaningful transformation. Two years ago, Income Capital Management was not a structured platform, not an international footprint, and not a growing client base across multiple jurisdictions. It was an idea. A simple but ambitious idea: to build an independent asset management platform focused on performance, discipline and long-term relationships. Today, on April 1st, that idea marks its second anniversary. From Concept to Platform Every investment firm starts with a vision. However, vision alone is not sufficient. Execution, adaptability and consistency are what transform a concept into a functioning platform. In the early stages, the challenge is not only technical or financial. It is structural. Building an asset management firm requires: Defining a clear investment philosophy Designing disciplined portfolio strategies Establishing operational processes Building trust with early clients Navigating regulatory environments Each of these elements must evolve simultaneously. Progress in one area without alignment in others creates instability. Over the past 24 months, the focus has been on building this structure step by step, ensuring that growth is supported by solid foundations. A Growing Client Base One of the most significant milestones in this journey has been the expansion of the client base. In just two years, Income Capital Management has reached more than 450 clients across different segments of the investment landscape: High Net Worth Individuals (HNWI) Family Offices Institutional investors Each of these client categories brings different expectations, constraints and objectives. HNWI clients often seek a balance between growth and capital protection, combined with clarity and accessibility. Family Offices typically require a more structured approach, focusing on wealth preservation, intergenerational planning and diversification. Institutional investors demand rigorous processes, transparency, and consistency in execution. Serving such a diverse client base requires flexibility, but also discipline. Strategies must be adaptable without losing coherence. International Presence: Prague and Dubai Geographical expansion has been another key element of growth. Establishing a presence in both Prague and Dubai reflects a strategic decision to operate across different financial ecosystems. Each location offers unique advantages: Prague provides access to European markets and regulatory frameworks Dubai offers connectivity to Middle Eastern and international investors Operating in multiple regions also introduces complexity. Different jurisdictions imply different regulatory requirements, client expectations and operational challenges. However, this complexity is also a source of strength. It enables diversification not only at the portfolio level, but also at the business level. From Local to Global The evolution from a local initiative to an international platform is not simply a matter of opening new offices. It involves: Adapting communication to global audiences Structuring investment solutions for cross-border clients Managing multi-currency exposure Aligning strategies with different economic environments This transition requires both operational capability and strategic clarity. Growth without structure creates fragility. Structure without growth creates stagnation. The objective has always been to balance both. The Next Step: New York After building a presence in Europe and the Middle East, the next natural step is expansion into the United States. The launch of Income Capital Management LLC in New York represents a significant milestone in this journey. The United States is one of the most competitive and sophisticated financial markets in the world. Entering this market requires not only ambition, but also readiness. The objective is clear: to expand business development and strengthen the firm’s international positioning. This expansion is not simply geographical. It is strategic. It reflects the intention to operate within a truly global investment framework. Not a Finish Line, but a Transition Milestones can be misleading. They may appear as points of arrival, but in reality they are often points of transition. The second anniversary of Income Capital Management is not a conclusion. It is a moment to evaluate progress, refine strategy and prepare for the next phase of growth. In asset management, sustainability matters more than speed. Rapid growth without discipline can create vulnerabilities. Controlled growth, supported by consistent processes, creates long-term resilience. What Has Driven This Journey Looking back at the past 24 months, several principles have consistently guided the development of the platform: Independence: maintaining objectivity in investment decisions Discipline: applying structured processes across strategies Client focus: prioritizing long-term relationships over short-term gains Adaptability: adjusting to changing market conditions These principles are not theoretical. They are operational. They influence how portfolios are constructed, how risks are managed, and how decisions are communicated. Delivering Consistent Value In financial markets, performance is often measured in short-term results. However, long-term value creation requires consistency. Clients do not only evaluate returns. They evaluate: Stability Transparency Risk management Communication Delivering consistent value means balancing these elements over time. It means avoiding unnecessary risk while still capturing opportunities. It means building trust not through promises, but through execution. Looking Forward The next phase of growth will likely bring new challenges. Markets will continue to evolve. Regulatory environments will change. Client expectations will increase. However, the core objective remains unchanged: to build a resilient, disciplined and globally relevant asset management platform. Growth will continue. Scaling will continue. But focus will remain on what truly matters: delivering value to clients over the long term. Conclusion Every journey in finance is built over time. The first 24 months of Income Capital Management represent the foundation of a broader vision. From a simple idea to an international platform, the process has been defined by execution, discipline and continuous development. The next chapters are still to be written. And the journey continues. LinkedIn Post: Read the original post on LinkedIn
Non-Discretionary Advisory: You Decide, We Empower
Non-Discretionary Advisory: You Decide, We Empower In the modern landscape of wealth management, investors are increasingly faced with a fundamental choice: delegate decisions entirely to a manager, or maintain control while navigating complex financial markets independently. Between these two extremes lies a model that is often underestimated but highly effective for sophisticated investors: non-discretionary advisory. At Income Capital Management, this approach is built around a simple but powerful principle: we provide the expertise, you retain the decision-making power. The Evolution of Investment Advisory Traditional wealth management models have historically been divided into two categories. On one side, discretionary management allows portfolio managers to make decisions on behalf of clients. This model offers convenience but often reduces transparency and client involvement. On the other side, self-directed investing gives clients full control, but requires significant time, knowledge and emotional discipline. Non-discretionary advisory represents a third path. It combines professional expertise with client control, creating a collaborative framework where decisions are informed, structured and aligned with long-term objectives. How the Non-Discretionary Model Works In a non-discretionary advisory model, the roles are clearly defined. The advisor provides research, analysis and strategic recommendations The client evaluates and approves each decision This structure ensures that every investment aligns with the client’s objectives, risk tolerance and personal preferences. Rather than delegating responsibility entirely, clients remain actively involved in shaping their financial journey. From Complexity to Clarity Financial markets today are more complex than ever. Investors must navigate multiple asset classes, global economic dynamics, currency exposure, regulatory environments and evolving risk factors. Without a structured framework, this complexity can lead to confusion, hesitation or reactive decision-making. The role of the advisor in a non-discretionary model is to simplify this complexity. At Income Capital Management, we provide: In-depth research across asset classes Scenario analysis based on macroeconomic conditions Clear investment recommendations Risk assessment and portfolio impact analysis This allows clients to make decisions with clarity rather than uncertainty. Maintaining Control Without Losing Depth One of the key advantages of non-discretionary advisory is that it preserves client independence without sacrificing analytical depth. Clients benefit from the same level of research and strategic thinking used in professional portfolio management, while retaining full authority over their capital. This is particularly valuable for: Entrepreneurs accustomed to making strategic decisions Professionals seeking transparency and control Family offices managing multi-generational wealth For these clients, investing is not just about returns. It is about alignment with broader financial and personal objectives. A Strategic Partnership, Not a Black Box Many traditional investment solutions operate as “black boxes.” Clients allocate capital, but have limited visibility into how decisions are made or how strategies evolve. Non-discretionary advisory takes a different approach. It creates a strategic partnership between advisor and client. Decisions are discussed, explained and evaluated collaboratively. This transparency builds trust and strengthens the investment process. Clients understand not only what is being done, but why it is being done. The Role of Scenario Analysis A central component of our advisory process is scenario analysis. Rather than relying on a single forecast, we evaluate how different market conditions could impact portfolio performance. This includes scenarios such as: Interest rate changes Economic slowdowns Geopolitical events Currency fluctuations By presenting these scenarios to clients, we provide a structured framework for decision-making. Clients are not reacting to uncertainty. They are prepared for it. Decision Support, Not Decision Replacement The objective of non-discretionary advisory is not to replace the client’s judgment. It is to support it. We provide the tools, data and insights necessary for informed decisions, but the final choice always remains with the client. This approach encourages responsibility, awareness and long-term thinking. It transforms investing from a passive experience into an active, informed process. Global Clients, Local Understanding Our advisory model is designed for international clients operating across multiple jurisdictions, including Europe, the United States and the UAE. These clients often face additional layers of complexity: Multiple currencies Different tax environments Cross-border investment structures Diverse regulatory frameworks Non-discretionary advisory allows us to tailor strategies to these specific contexts while maintaining a consistent global framework. The Psychological Advantage of Empowerment One of the most underestimated benefits of this model is psychological. Investors who are actively involved in decision-making tend to feel more confident and less reactive during market volatility. They understand the rationale behind their portfolio structure and are therefore more likely to maintain discipline during challenging periods. Empowered clients make better decisions. And over time, they build stronger financial outcomes. Transparency as a Competitive Advantage In an industry often characterized by complexity and opacity, transparency becomes a key differentiator. Non-discretionary advisory ensures that: All recommendations are clearly explained All risks are explicitly identified All decisions are documented and understood This level of transparency strengthens trust and improves long-term client relationships. Conclusion Non-discretionary advisory is not simply an alternative investment model. It is a philosophy. It reflects the belief that clients should remain at the center of their financial decisions, supported by professional expertise rather than replaced by it. In a world of increasing complexity, this approach offers clarity, structure and empowerment. You decide. We empower. And together, we build stronger investment journeys. LinkedIn Post: Read the original post on LinkedIn
Building a High-Yield Strategy Without Losing Sleep
Building a High-Yield Strategy Without Losing Sleep By Nicola Pinchi — Income Capital Management There is a phrase that gets thrown around a lot in investment circles: “yield is king.” And in an environment where investors are perpetually hungry for income, it is easy to understand why. The promise of a high coupon, a double-digit return, or a fat dividend can cloud judgement in ways that more modest returns never could. But here is the uncomfortable truth: not all yield is created equal, and chasing the wrong kind can cost you far more than it ever pays. At IncomeCapital Management, when we build High Yield strategies, we do not start with the coupon. We start with the question: what could go wrong? Yield Is a Compensation, Not a Gift The first principle any serious income investor must internalize is that yield is compensation for risk. When a bond or credit instrument offers a high coupon, it is because the market perceives meaningful risk in that issuer — default risk, liquidity risk, sector risk, or a combination of all three. The higher the yield relative to safer alternatives, the louder the market is warning you about something. This does not mean High Yield is to be avoided. Far from it. Properly managed, High Yield credit is one of the most effective tools for generating consistent, meaningful income over time. But “properly managed” is doing a lot of work in that sentence. The discipline lies in understanding exactly what risk you are being paid to take — and deciding whether the compensation is fair. The Four Pillars: Quality, Diversification, Liquidity, and Downside Scenarios When we construct our High Yield portfolio, four factors sit at the heart of every decision. Issuer quality comes first. Not every BB-rated or B-rated credit is the same. We spend significant time on fundamental analysis — understanding a company’s cash flow generation, debt coverage, sector positioning, and management track record. A high-yield issuer with strong free cash flow and a credible deleveraging path is a very different animal from one that is leveraged to the hilt with no clear path to refinancing. We prefer the former, even if the coupon is somewhat lower. Diversification is the second pillar, and it is non-negotiable. Concentration risk in High Yield is particularly dangerous because defaults, when they happen, tend to cluster — by sector, by rating cohort, by macro regime. A portfolio that is too heavy in energy, real estate, or any single geography can experience drawdowns that feel more like equity crashes than bond corrections. We build for breadth, ensuring that no single issuer, sector, or country overwhelms the portfolio. Liquidity is the often-overlooked third pillar. In benign market conditions, liquidity in High Yield looks fine. Spreads are tight, bid-ask margins are reasonable, and selling a position feels effortless. But in a risk-off environment — a credit crunch, a rates spike, a geopolitical shock — High Yield liquidity can evaporate quickly. Investors who have built illiquid portfolios in search of extra yield find themselves trapped precisely when they most need flexibility. We size positions carefully and maintain a liquidity buffer that allows us to act, not react, when markets dislocate. Downside scenarios are the fourth and perhaps most important pillar. Before any position is added to the portfolio, we run the stress test: what happens to this instrument if the issuer’s earnings fall 30%? What if the sector re-rates by 200 basis points? What if we need to exit in a hurry? If the answers to those questions produce outcomes that keep us awake at night, the position does not belong in the portfolio — regardless of how attractive the headline yield appears. High Yield Within a Multi-Asset Framework One of the most powerful tools for managing High Yield risk is context — specifically, the context of a broader, multi-asset portfolio. At IncomeCapital, we do not run High Yield in isolation. We combine our High Yield Fund with other return engines: Forex strategies, Real Estate income, and Global Growth equities. This multi-asset architecture serves a critical purpose. High Yield credit tends to suffer during periods of economic stress and risk aversion — exactly the same environments where certain Forex strategies and defensive equity positions can provide ballast. By blending these uncorrelated income streams, we reduce the portfolio’s sensitivity to any single risk factor. The result is a smoother ride for investors: meaningful income, with volatility that does not trigger panic selling at the worst possible moment. Overexposure to a single asset class — even a well-managed one — is a structural vulnerability. Diversification across strategies is not just a nice-to-have; it is the architecture that makes sustainable income generation possible over full market cycles. The “Sleep Test” We have an informal rule at IncomeCapital that we call the “sleep test.” It is simple: if a position or a yield level makes you nervous, it is already too expensive. This might sound like a soft heuristic in a world of sophisticated quantitative models, but it captures something important. Nervousness about a yield is usually a signal that the embedded risk has not been fully priced or fully understood. When an investor reaches for yield despite a nagging sense of unease, they are often discounting low-probability but high-severity risks — the kind that do not show up in historical data until the moment they actually occur. Discipline means walking away from attractive coupons when the risk-reward does not justify the exposure. It means accepting slightly lower income in exchange for a portfolio you can hold through volatility without second-guessing every market move. Over time, this approach — quality-focused, diversified, liquidity-aware, and scenario-tested — consistently outperforms the yield-chasing alternative, not just on a risk-adjusted basis, but in absolute terms. The Goal: Meaningful Income, Peaceful Nights The objective of a well-constructed High Yield strategy is not to maximize the coupon on any given day. It is to generate meaningful, sustainable income over time — income that compounds, that survives credit cycles, and that
What I Learned from My First Market Crash
What I Learned from My First Market Crash By Paolo Volpicelli — Income Capital Management There are moments in a professional career that divide time cleanly into before and after. For investment managers, the first real market crash is one of them. Not the crashes you study in textbooks, not the drawdowns you model in spreadsheets — but the real thing. The one where client phones ring at all hours, where liquidity evaporates overnight, and where even the most carefully constructed portfolio feels suddenly fragile. My first market crash changed the way I design every strategy. Not because it destroyed everything we had built — it did not — but because it exposed every assumption I had not questioned hard enough. Here are the three lessons that have stayed with me ever since, and that now sit at the foundation of every portfolio we manage at Income Capital Management. Lesson One: Never Ignore Liquidity In calm markets, liquidity feels like a given. Assets trade freely, bid-ask spreads are tight, and the idea of not being able to exit a position seems almost abstract. The crash cured me of that illusion permanently. When fear takes hold of a market, the first thing that disappears is not price — it is the buyer on the other side of the trade. Positions that looked perfectly liquid on a Tuesday morning can become impossible to exit by Thursday afternoon. The investors who suffer most in a crash are rarely those with bad assets; they are often those with good assets held in illiquid structures, unable to rebalance, meet margin calls, or seize the opportunities that dislocated markets inevitably create. Since that experience, liquidity management has been a non-negotiable feature of everything we build. We size positions with exit conditions in mind — not just entry conditions. We maintain cash or near-cash buffers at the portfolio level. And we run regular liquidity stress tests: not just “what is the mark-to-market today?” but “what can we actually sell in the next 48 hours if we need to?” The answer to that second question is the one that matters when a crash arrives. Lesson Two: Never Underestimate Emotions The second lesson was more humbling, because it was not about the market — it was about people. Including, at times, myself. The behavioral finance literature has documented for decades what any practitioner learns quickly in a real crisis: human beings are not rational optimizers when money is on the line and uncertainty is high. Fear of loss is roughly twice as powerful as the pleasure of an equivalent gain. When portfolios are falling and headlines are screaming, the emotional pressure to sell — to “do something” — becomes almost unbearable, even for experienced professionals. I watched clients who had explicitly agreed to a long-term strategy demand to liquidate everything at the worst possible moment. I watched myself second-guess decisions that were perfectly sound simply because the noise around them had become deafening. The lesson was clear: emotions are not a sign of weakness. They are a structural feature of how human beings process risk under uncertainty. If you do not account for them in advance, they will override your strategy at the moment it matters most. This is why at Income Capital Management we invest significant time in what happens before a crisis, not during it. We have detailed conversations with every client about their real risk tolerance — not the theoretical number on a questionnaire, but the visceral answer to “how would you feel if this portfolio fell 20% in three months?” We build portfolios that clients can hold through volatility, not just portfolios that look optimal in a spreadsheet. And we establish clear communication protocols so that when markets deteriorate, the response is prepared, not improvised. Lesson Three: Never Assume “This Time Is Different” The most dangerous phrase in finance has not changed in a century: this time is different. Every speculative excess, every credit bubble, every irrational rally eventually produces a cohort of intelligent, well-credentialed people arguing that the old rules no longer apply — that structural changes in the economy, in technology, or in monetary policy have permanently altered the relationship between risk and return. They are always wrong. Not because markets cannot evolve, but because the underlying human dynamics — greed, fear, herding behavior, the compression of risk premiums in good times and the violent repricing that follows — repeat with remarkable consistency across decades and asset classes. The crash I lived through was unique in its specific triggers. It was not unique in its fundamental mechanics. Studying market history is not an academic exercise. It is one of the most practical risk management tools available. Knowing how previous credit cycles unwound, how liquidity crises have propagated, how long recoveries have historically taken — this knowledge does not predict the future, but it builds the mental resilience to avoid being surprised by it. At Income Capital Management, market history informs every scenario analysis we run and every stress test we apply to our strategies. From Lessons to Practice: Stress Tests, Contingency Plans, and Honest Conversations The three lessons above are not simply philosophical reflections. They translate directly into how we operate. Stress tests are now a standard part of every strategy we design. Before any portfolio goes live, we model what happens under a range of adverse scenarios: sharp equity drawdowns, credit spread widening, currency dislocations, liquidity freezes. The goal is not to predict which scenario will occur — it is to ensure that no single scenario produces an outcome that would force a client to abandon their strategy at the worst possible moment. Contingency plans are the operational response layer. For each stress scenario, we pre-define the actions we would take: which positions would be reduced first, which hedges would be activated, how client communication would be structured. Having these plans in place before a crisis means that when volatility arrives, we are executing a prepared response — not making high-stakes
Real Estate Fund: From Bricks to Strategy | Income Capital Management
Real Estate Fund: From Bricks to Strategy By Paolo Volpicelli — Income Capital Management When most people think about investing in real estate, they picture a single property: an apartment to rent out, a commercial unit in a growing city, perhaps a holiday home that doubles as an asset. It is a familiar mental model, and it has served generations of investors reasonably well. But it carries hidden costs that are rarely discussed candidly — concentration risk, illiquidity, management burden, and the kind of idiosyncratic exposure that no amount of local market knowledge can fully insulate you from. At Income Capital Management, we designed our Real Estate Fund on a fundamentally different premise: real estate is not about buying a property. It is about building a strategy. The Problem with Single-Property Investing The appeal of owning a single investment property is understandable. It is tangible, visible, and carries the psychological comfort of something you can walk through and inspect. But from a portfolio construction perspective, a single property is one of the most concentrated positions an investor can hold. Consider what you are actually exposed to when you own one building or one unit. Your returns depend entirely on the performance of a single asset in a single location, often let to a single tenant or a narrow pool of tenants. If the local market softens, if the tenant vacates, if a structural issue emerges, or if regulatory changes affect that specific type of property — the entire investment is impacted. There is no offset, no diversification, no institutional buffer. You bear one hundred percent of a very specific set of risks. Then there is the operational reality. Managing a property — even a single one — requires time, expertise, and ongoing attention. Tenant relations, maintenance, legal compliance, insurance, financing, tax optimization: these are not passive activities. For most investors, the hidden cost of direct property ownership is not just financial. It is the cost of time and mental bandwidth that could be deployed elsewhere. What a Real Estate Fund Actually Provides A professionally managed real estate fund solves the core structural problems of single-property investing by providing something that individual investors almost never have access to on their own: an institutional portfolio. Our Real Estate Fund gives investors exposure to professionally selected projects and assets across diversified tenants and sectors. Rather than concentrating risk in a single building, investors participate in a portfolio that spans different property types — residential, commercial, logistics, hospitality — and different geographies, with each position selected through rigorous due diligence and monitored on an ongoing basis. The difference is not cosmetic. Diversification across tenants and sectors means that the underperformance or vacancy of any single asset has a limited impact on the overall portfolio. A logistics warehouse in one market does not correlate perfectly with a residential development in another. A commercial tenant exiting one property does not create a domino effect across the fund. The portfolio is engineered to be resilient precisely because no single decision, asset, or tenant can determine its fate. This is what we mean when we say we turn bricks into a coherent plan — not isolated decisions. A Strategic Pillar for Investors in Europe, USA and UAE Real estate’s role in a well-constructed portfolio has always been about more than income. It offers three distinct contributions that few other asset classes can replicate simultaneously. Income generation is the most visible benefit. Rental income from a diversified property portfolio provides a relatively stable cash flow stream — one that tends to be less correlated with equity market volatility than dividends or bond coupons. For income-focused investors, particularly those in or approaching retirement, this stability has real value. Partial inflation protection is the second contribution. Property values and rental income have historically shown a meaningful correlation with inflation over medium-to-long time horizons. When the cost of goods and services rises, so do the replacement costs of buildings, the rents that tenants are willing or required to pay, and the nominal value of well-located assets. Real estate is not a perfect inflation hedge — no asset class is — but it provides meaningful protection that pure financial assets often lack. Tangible value is the third pillar. Unlike equities or bonds, a property portfolio is backed by real physical assets with intrinsic utility. People need places to live, work, store goods, and conduct commerce. This demand does not disappear in a financial crisis. The tangible nature of real assets provides a floor under valuations that purely financial instruments do not have, and it gives investors a different kind of psychological anchor during periods of market turbulence. For our clients across Europe, the USA and the UAE, the Real Estate Fund serves as exactly this kind of strategic pillar — a complement to financial assets that provides income, inflation resilience, and asset-backed stability within a broader multi-asset framework. Institutional Access, Professional Management One of the fundamental inequalities of traditional real estate investing is access. The best projects — premium commercial developments, large-scale residential schemes, institutional-grade logistics assets — are not available to individual investors. They require substantial minimum commitments, deep market networks, and the operational infrastructure to manage complex assets across multiple jurisdictions. These are barriers that effectively reserve the highest-quality real estate opportunities for institutional players. Our Real Estate Fund changes this equation. By pooling capital and applying institutional-grade due diligence to asset selection, we give our clients access to the kind of portfolio that would otherwise require tens of millions in direct investment and a dedicated property management team to assemble. Every asset in the fund is selected through a structured evaluation process: market analysis, financial modelling, tenant quality assessment, legal review, and stress testing under adverse scenarios. Every position is monitored continuously, with portfolio-level decisions made by professionals whose full-time focus is exactly this. The investor benefits from this expertise without inheriting the operational complexity that comes with direct ownership. Real Estate Within the Income Capital Framework The Real
Reading Central Banks: A Practical Guide for Investors | Income Capital Management
Reading Central Banks: A Practical Guide for Investors By Nicola Pinchi — Income Capital Management Few forces in global finance move markets as consistently and as broadly as central bank decisions. A single press conference from the Federal Reserve, the European Central Bank, or the Bank of England can reprice bonds across the entire yield curve, send currencies surging or sliding, trigger equity rotations worth hundreds of billions, and shift the risk appetite of institutional investors worldwide — all within the span of a few hours. And yet, for most investors, central bank communication remains one of the most frustrating aspects of financial markets to navigate. The language is deliberately cautious, laden with caveats, and often designed as much to manage market expectations as to convey actual policy intent. After each meeting, headlines compete to offer the definitive interpretation, analysts disagree on the implications, and investors are left wondering what — if anything — they should actually do. At Income Capital Management, we believe the answer is not to react faster to central bank announcements. It is to understand which signals genuinely matter — and to build that understanding into strategic decisions long before the next meeting takes place. Why Monetary Policy for Investors Cannot Be Ignored The influence of central banks on investment portfolios is not a recent phenomenon, but it has become more pronounced in the past two decades. Since the 2008 financial crisis, central bank policy has been the dominant driver of asset valuations across virtually every major market. Ultra-low interest rates and quantitative easing programmes inflated bond prices, compressed credit spreads, boosted equity multiples, and sent real estate values to historic highs. When that cycle eventually reversed — as it did sharply from 2022 onwards — the damage across asset classes was equally broad. Understanding the direction of monetary policy is therefore not an academic exercise for macroeconomists. It is a practical necessity for anyone managing a diversified portfolio. Whether you hold bonds, equities, currency positions, or real assets, the path of interest rates and central bank liquidity conditions will influence your returns, your risk profile, and your optimal asset allocation in ways that no bottom-up analysis of individual securities can fully compensate for. The challenge is not recognising this fact. The challenge is developing a systematic, repeatable framework for extracting actionable insight from the noise of central bank communication — without getting lost in every nuance of every statement. The Four Signals That Actually Matter Over years of integrating monetary policy analysis into portfolio management across Forex, High Yield, Global Growth and Real Estate, we have found that four signals consistently carry the most predictive weight. Everything else is largely commentary. Inflation trends are the bedrock. Central banks exist primarily to manage price stability, and their policy decisions are ultimately a response to what inflation is doing and where it is expected to go. When inflation is rising above target, the policy bias will lean restrictive — higher rates, tighter liquidity conditions, a headwind for duration-sensitive assets. When inflation is falling towards or below target, the bias shifts accommodative. Tracking the evolution of core inflation, services inflation, and inflation expectations — rather than headline CPI alone — gives a far more reliable read on the direction of travel than any central bank statement. Policy direction and pace matter as much as the absolute level of rates. Markets do not reprice because rates are high or low in absolute terms; they reprice when the direction or pace of change surprises. A central bank that signals it is done hiking — even at elevated rates — is providing a very different environment for risk assets than one that is actively tightening. Learning to identify genuine policy pivots, as distinct from tactical pauses or communication management, is one of the most valuable skills a macro-aware investor can develop. Liquidity conditions are the transmission mechanism that connects monetary policy to real market behaviour. Beyond the policy rate itself, the size and composition of central bank balance sheets, the pace of quantitative tightening or easing, and the functioning of repo and money markets all determine how easily credit flows through the financial system. Periods of ample liquidity tend to compress risk premiums and support asset prices. Periods of tightening liquidity have the opposite effect — often before the impact shows up in economic data. Monitoring these conditions provides an early warning system that pure rate analysis misses. Central bank credibility is the most intangible of the four signals, but ultimately the most powerful. A central bank that the market believes will do what it says — that has a track record of hitting its inflation target, communicating consistently, and following through on its commitments — has enormous capacity to stabilise expectations without dramatic policy action. A central bank that has lost credibility, or that sends confused signals, generates persistent uncertainty that increases volatility across all asset classes. Assessing credibility requires a qualitative overlay on top of quantitative data, but it is essential to getting the framework right. From Analysis to Portfolio Decisions Understanding these four signals is necessary. Knowing how to translate them into portfolio positioning is what makes the analysis useful. In our Forex strategies, monetary policy divergence between central banks is the primary driver of medium-term currency moves. When the Fed is tightening while the ECB is on hold, or when the Bank of Japan is normalising while the Bank of England is cutting, these differentials create directional Forex opportunities that can be captured systematically. The key is distinguishing between divergences that are already priced in and those that the market has not yet fully discounted. In our High Yield credit allocations, the liquidity cycle is particularly critical. Loose monetary conditions compress spreads and reduce default risk by making refinancing easier for leveraged borrowers. Tightening conditions have the opposite effect: spreads widen, refinancing becomes more expensive, and the weakest credits face genuine stress. Mapping the liquidity cycle allows us to adjust credit quality and duration positioning well

