Portfolio Risk Management: A Complete Guide to Protecting Capital in Volatile Markets
Portfolio Risk Management: A Complete Guide to Protecting Capital in Volatile Markets Every investor eventually learns the same lesson, usually the hard way. Returns attract attention, but risk decides outcomes. A portfolio that grows steadily for five years can lose half of that progress in five weeks if the risk behind it was never properly understood. This is why portfolio risk management sits at the center of everything we do at Income Capital Management. It is not a department, a report or a compliance requirement. It is the discipline that determines whether a strategy survives contact with real markets. The past several weeks have offered a vivid reminder of how quickly conditions can change. A stronger than expected US jobs report pushed bond yields sharply higher, equity indexes fell across Europe and the United States, technology names that had led the market for months suffered heavy profit taking, and the dollar reasserted its role as a safe haven. Investors who had built their portfolios on the assumption of calm conditions discovered, once again, that calm is temporary. Investors who had built their portfolios around a serious risk framework were able to watch the same events with composure. This guide brings together the principles, tools and habits that define professional portfolio risk management. It draws on the themes we have been discussing with clients and partners throughout recent months: the difference between risk and noise, the central role of correlation, the value of stress testing, the strategic importance of liquidity, the stabilizing function of real assets, and the growing contribution of technology and artificial intelligence to the way risk is measured and managed. It is a long read by design. Risk is a subject that rewards depth, and shortcuts in understanding tend to become losses in practice. What Portfolio Risk Management Really Means Ask ten investors to define portfolio risk management and you will receive ten different answers. Some will talk about stop losses. Some will mention diversification. Some will describe insurance products or hedging strategies. All of these answers touch a piece of the truth, but none of them captures the whole picture. At its core, portfolio risk management is the process of deciding, in advance and with full awareness, how much uncertainty a portfolio should carry, where that uncertainty should come from, and what should happen when reality tests those decisions. It is a framework, not a product. It begins before the first investment is made and it never stops operating as long as capital remains at work. A useful way to think about it is to reverse the usual order of questions. Most investors start by asking what they can earn. Professional investors start by asking what they can lose, under which circumstances, and whether that loss would be survivable, both financially and psychologically. Only after those questions have honest answers does the conversation move to expected returns. This ordering is not pessimism. It is the foundation of durability. In our own work across Forex, Real Estate, Physical Gold, Global Growth and High Yield strategies, every allocation decision passes through the same filter. What does this position add to total portfolio risk? How does it behave when markets are stressed? What is the realistic worst case over a meaningful horizon? How quickly could it be reduced or closed if conditions demanded it? A position that cannot answer these questions clearly does not enter the portfolio, no matter how attractive its potential return appears. Risk Is Multidimensional One of the most common mistakes in portfolio risk management is treating risk as a single number. Volatility is the measure most investors know, and it is useful, but it describes only one dimension of risk: how much prices move around their average. A portfolio can have low volatility and still carry enormous risk if that risk is hidden in illiquidity, leverage, concentration or credit exposure. Professional risk management considers at least five distinct dimensions. Market risk describes how a portfolio responds to broad movements in equities, rates, currencies and commodities. Credit risk measures the possibility that borrowers or counterparties fail to meet their obligations. Liquidity risk captures how difficult and costly it would be to convert positions into cash when needed. Concentration risk reflects dependence on a single asset, sector, region or theme. Operational and structural risk covers everything from custody arrangements to the legal structure of the vehicles used. Each of these dimensions can be managed, but only if it is first measured and acknowledged. A portfolio review that looks only at performance and volatility is like a medical checkup that measures only height and weight. It produces a number, but it misses most of what matters. The Goal Is Not Zero Risk It is worth being explicit about something that experienced investors understand instinctively. The goal of portfolio risk management is not to eliminate risk. A portfolio with no risk has no return beyond cash, and over time inflation quietly converts that apparent safety into a guaranteed loss of purchasing power. Risk is the raw material of return. The question is never whether to take risk, but which risks to take, in what size, and with what compensation. This is why we describe our approach as risk budgeting rather than risk avoidance. Every portfolio has a total amount of risk that is appropriate for its owner, defined by objectives, time horizon, liquidity needs and emotional tolerance. That budget is then spent deliberately, allocated to the exposures that offer the best compensation per unit of risk. Spending the budget on a concentrated bet in a single overheated sector is one choice. Spreading it across genuinely independent sources of return is another. The budget is the same. The outcomes, over time, are radically different. Risk Versus Noise: The Distinction That Protects Both Capital and Composure Markets produce movement every day. Prices rise and fall, headlines compete for attention, and commentary fills every available channel. Most of this movement is noise: temporary fluctuation that carries no lasting information about the value
Real Estate as a Portfolio Stabilizer: A Complete Guide to Diversification with Property
Most investors understand, at least in theory, that putting everything into a single asset class is a mistake. Yet when you look at how private portfolios are actually constructed, you find something curious: real estate tends to be treated as an afterthought, a parallel world that operates separately from the main investment strategy. It sits in its own mental category, governed more by instinct, local familiarity or a broker’s recommendation than by any coherent portfolio logic. This disconnect is costly, and it persists largely because real estate portfolio diversification is one of the most discussed but least rigorously applied concepts in wealth management. What follows is a serious attempt to address that gap. This article is not a general case for property investment. It is a detailed examination of how real estate, when properly selected and integrated, changes the behavior of a multi-asset portfolio in ways that few other asset classes can replicate. We will cover the mechanics of diversification, the role of income generation, the importance of quality and location, the specific challenges that international investors face, and the discipline required to manage liquidity and risk within a real estate allocation. Throughout, the emphasis is on substance over simplicity: real estate portfolio diversification is a precise practice, not a general principle. What Portfolio Stabilization Actually Means Before examining real estate specifically, it is worth clarifying what stabilization means in a portfolio context. Many investors use the term loosely, treating it as a synonym for safety or capital preservation. In practice, stabilization refers to something more specific: the reduction of portfolio-level volatility without a corresponding reduction in expected return, achieved by combining assets that do not move in lockstep with each other. The mathematical foundation of this idea is correlation. When two assets have a correlation of 1.0, they move perfectly together, and combining them offers no diversification benefit. When their correlation is negative or close to zero, their movements offset each other, smoothing the overall portfolio trajectory. The stabilizing power of any asset depends not just on its individual return characteristics but on how those characteristics interact with everything else in the portfolio. Real estate occupies an interesting position in this framework. Its correlation with equities is moderate rather than negligible, meaning it does not completely decouple from stock market movements, particularly in periods of severe stress. But over normal market cycles, property returns follow a path driven by different forces: rental income, local supply and demand dynamics, tenant creditworthiness, interest rate levels, and the specific economic conditions of the sectors and geographies involved. These forces create a return stream that complements equities, fixed income, and other asset classes in ways that measurably improve portfolio efficiency. Understanding this is the difference between adding real estate to a portfolio as a diversifier and adding it as a separate bet. A diversifier is chosen for what it does to the whole. A standalone bet is chosen for what it is expected to do on its own. The former is a portfolio decision. The latter is speculation dressed up in respectable language. The Historical Case for Real Estate in Multi-Asset Portfolios Decades of data across multiple countries and property types support the inclusion of real estate as a structural element in diversified portfolios. In developed markets, commercial real estate has historically delivered long-term total returns in the range of six to nine percent annually, combining income yields of four to six percent with modest capital appreciation. These returns have been achieved with lower volatility than equities and with patterns of drawdown that, while significant in downturns like 2008 to 2009, tend to recover over longer cycles than many investors expect. The income component deserves particular attention. Unlike equities, where dividends are discretionary and can be suspended, real estate typically generates contractual cash flows through lease agreements. Commercial leases in particular often have durations of three, five, or ten years, creating an income stream that is more predictable than almost anything available in public markets at comparable yield levels. This predictability has significant value for investors with defined cash flow needs, including family offices, pension-like structures, and high-net-worth individuals funding ongoing expenditures. During periods of rising inflation, real estate has historically maintained its purchasing power better than most financial assets. Property values and rents tend to rise with general price levels, often with contractual provisions for annual rent escalation built directly into lease agreements. The result is an asset that provides a degree of inflation protection that bonds, in particular, are unable to offer. This characteristic becomes especially relevant in the current environment, where investors who rely too heavily on fixed income face real return erosion that is difficult to recover. The historical evidence also shows that real estate’s return cycle is genuinely different from that of equities. Property values do not recalibrate daily in response to earnings announcements or central bank statements. They respond to physical supply and demand, to construction cycles that take years to play out, and to economic conditions that affect businesses’ need for space. This slower dynamic creates periods when real estate performs well precisely when equity markets struggle, and vice versa, which is exactly what a portfolio stabilizer should do. Understanding Real Estate’s Correlation Behavior One of the most important and least understood aspects of real estate portfolio diversification is the way correlation between property and other assets changes depending on market conditions. This phenomenon, sometimes called correlation instability, affects virtually all asset classes but has specific implications for real estate. Under normal conditions, direct real estate, meaning physical property held directly or through private vehicles, exhibits correlations with equity markets that are low to moderate, typically ranging from 0.2 to 0.4 depending on the measurement period and the specific property types involved. This is a meaningful diversification benefit. A portfolio that is sixty percent equities and twenty percent direct real estate behaves substantially differently from a pure equity portfolio when markets are in normal mode. During severe crises, correlations tend to rise across most
International Asset Management in New York: Inside Income Capital Management’s Expansion to Wall Street
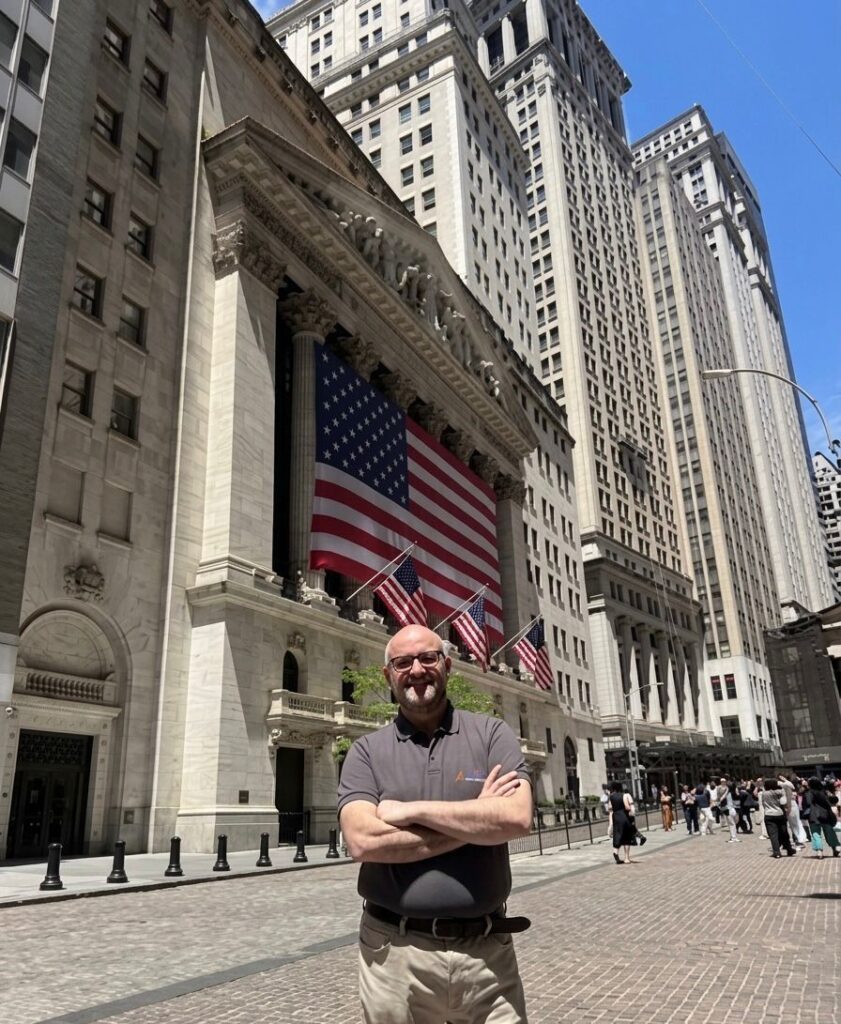
There is a particular kind of clarity that comes from standing in Lower Manhattan on a Tuesday morning, watching the financial district come alive. The streets around Wall Street and Broad Street fill early, the conversations are focused, and the density of financial knowledge per square meter is probably higher here than anywhere else on earth. For anyone who has spent years managing capital across international markets, this environment is not just symbolic. It is genuinely useful. It is why Income Capital Management’s decision to establish a New York presence was not an act of ambition for its own sake but a deliberate response to what our clients need and what the evolution of international asset management requires. This article is about that decision and the broader forces that make New York an indispensable hub for international portfolio management in 2025. But it is also, more fundamentally, about the nature of international asset management itself: what it means to build portfolios that function across borders and currencies, why proximity to global financial networks matters for the quality of investment decisions, and how the specific combination of access, relationships, and market intelligence available in New York changes what is possible for international investors. We will examine all of this in detail, because the opening of a new office is only interesting if it reflects something real about how investment management is evolving and what clients stand to gain from it. Why New York Remains the Center of Global Finance The argument that New York’s financial dominance is in decline has been made repeatedly over the past two decades, and it has been repeatedly wrong. London’s post-Brexit reconfiguration, the rise of Asian financial centers, and the geographic diversification of technology companies that have disrupted financial services have all prompted speculation that New York might lose its singular position. The evidence, however, tells a different story. New York remains home to the largest concentration of capital markets activity in the world. The New York Stock Exchange and NASDAQ together list more companies by market capitalization than any other exchange or combination of exchanges globally. The US Treasury market, centered on relationships and infrastructure located in New York, is the deepest and most liquid government bond market in existence, serving as the reference point for risk-free rates worldwide. The New York Federal Reserve plays a unique role in implementing monetary policy and maintaining financial stability, and its relationships with global central banks run through New York in ways that have no equivalent elsewhere. Beyond these structural facts, New York’s position as a financial hub is reinforced by the sheer concentration of talent and knowledge that has accumulated there over more than a century of market development. The largest global investment banks, asset managers, hedge funds, private equity firms, law firms, and accounting practices all maintain their most important offices in New York. This concentration creates network effects that are self-reinforcing: the best investment professionals want to be where the most interesting opportunities are, and the most interesting opportunities are where the best professionals are. For an alternative investment manager with international clients and a focus on multi-asset portfolio construction across Forex, real estate, fixed income, and global equities, New York provides access to counterparties, market intelligence, and professional relationships that are simply not available at the same depth or quality elsewhere. The practical advantage of being able to meet face-to-face with bank trading desks, fund managers, real estate advisors, and industry specialists in a single city, rather than dispersing these interactions across multiple markets, is significant and measurable. The Geography of Financial Trust Investment management is fundamentally a trust-based business. Clients entrust their capital to managers who have demonstrated the competence, integrity, and alignment of interests necessary to manage it responsibly. Building this trust takes time, consistency, and the kind of relationship depth that is difficult to create remotely. The geographic dimension of trust-building in finance is real and persistent, even in an age of video calls and digital communications. For international investors, particularly those based in Europe, Asia, or the Middle East, the decision to entrust capital to a manager requires a level of confidence that goes beyond reviewing performance records and marketing materials. It requires understanding the manager’s culture, meeting their team, observing how they handle difficult questions, and assessing whether their values and approach align with the investor’s own principles. These assessments are far more reliably made in person than through any form of remote interaction. A New York presence does not replace the importance of meeting clients in their home markets. But it creates a second important node in the relationship network: a location where clients who travel to New York for other purposes can meet the Income Capital Management team in a setting that reflects the firm’s positioning in the international financial community. It also creates opportunities to engage with the broader investment ecosystem in New York, including other asset managers, family offices, allocators, and industry groups, in ways that build the firm’s visibility and reputation among sophisticated international investors. The geography of trust also matters for the quality of information that investment managers receive. In a world where much financial information is commoditized and publicly available, the edge comes from relationships with people who have relevant expertise, direct market access, or proprietary perspectives. These relationships are built through repeated personal interaction over time, and they cluster geographically in financial centers where the relevant professionals are concentrated. A team that can walk into a meeting with a major bank’s trading desk, visit a potential real estate investment in person, or attend an industry dinner where informal conversations reveal market dynamics that are not yet public is better informed than one operating purely remotely. What Proximity to Wall Street Actually Delivers For those unfamiliar with the practical workings of institutional investment management, the appeal of being located near Wall Street might seem abstract. In practice, it translates into a series of concrete advantages that compound over time into
Long Term Investing in 2026: Why Simplicity, Diversification and Risk Discipline Matter More Than Ever
Long Term Investing in 2026: Why Discipline and Simplicity Matter More Than Ever One of the easiest mistakes investors can make is believing that good investing should feel exciting all the time. Financial markets today move inside a constant flow of information where every inflation release, political statement, central bank meeting or geopolitical tension immediately becomes urgent news. The speed of information creates the impression that portfolios constantly need to be adjusted and that successful investing depends on reacting faster than everyone else. In reality, long term investing usually works very differently. Most of the time, strong results do not come from dramatic decisions. They come from consistency, discipline and the ability to remain rational while markets become emotional. That sounds simple in theory, but in practice it becomes surprisingly difficult when volatility increases and uncertainty dominates headlines for weeks or months. This has been particularly visible throughout 2026. Inflation concerns, changing interest rate expectations, geopolitical instability and uneven global growth have created an environment where many investors feel permanently uncomfortable. Markets continue moving between optimism and caution, often reacting aggressively even to relatively small economic surprises. In this type of environment, investors naturally begin asking themselves difficult questions. Should exposure be reduced. Should more cash be held. Is diversification still working. Are markets becoming too risky. Is this temporary volatility or the beginning of a larger structural shift. These are legitimate concerns. But they also highlight an important reality about investing. The biggest challenge is often not the market itself. The biggest challenge is how investors behave while markets become uncertain. Why Investors Often Overreact to Macro Data Modern markets react instantly to economic information. Inflation numbers, employment data, GDP revisions and central bank comments are immediately reflected across bonds, currencies and equities. The problem is that investors sometimes interpret every data release as if it completely changes the long term outlook. Good macro analysis does not work that way. A single inflation report rarely tells the full story. A single weak economic number does not automatically signal recession. Strong markets are not built on isolated data points. They are built on trends, consistency and broader economic conditions. One of the most dangerous habits in investing is emotional interpretation of short term information. Investors see a negative headline and immediately feel pressure to act. The reality is that markets frequently overreact before finding balance again once more context becomes available. This is why serious macro analysis focuses less on isolated numbers and more on direction. The real objective is understanding whether the broader environment is improving, deteriorating or simply moving through temporary noise. When investors lose that perspective, portfolios become reactive instead of strategic. Diversification Is More Important Than Most Investors Realize Diversification is one of the most repeated concepts in finance, but it is also one of the least understood. Many people think diversification simply means owning more positions. In reality, owning many assets that all react the same way during stress is not true diversification. It only creates the illusion of safety. Real diversification comes from combining exposures that behave differently under changing market conditions. Currencies react differently to inflation and rates compared to equities. Real assets respond differently to liquidity conditions compared to credit markets. Gold behaves differently during geopolitical uncertainty than growth-oriented sectors. The objective is not to own more things. The objective is to avoid depending too heavily on one single outcome. This is particularly important during periods like 2026 where markets continue shifting rapidly between different macro narratives. Some weeks inflation dominates attention. Other weeks investors focus on growth concerns, geopolitical risk or liquidity expectations. A concentrated portfolio becomes vulnerable very quickly when the dominant narrative changes unexpectedly. A diversified portfolio does not eliminate volatility completely. That would be impossible. What it does is create resilience. It reduces fragility and gives investors more flexibility to navigate uncertainty without making emotional decisions every time conditions change. Why Simplicity Often Leads to Better Decisions One of the more interesting patterns in wealth management is that investors often associate complexity with sophistication. There is a tendency to believe that a complicated portfolio must automatically be more advanced or more intelligent. In practice, complexity often creates confusion rather than quality. Portfolios overloaded with unnecessary structures, excessive overlapping exposures or products that investors do not fully understand usually become difficult to manage emotionally during volatile periods. This matters much more than people realize. When markets become unstable, investors naturally search for clarity. If a portfolio feels confusing, every market movement starts generating anxiety. Investors become more vulnerable to impulsive decisions because they are no longer fully confident about what they own or why they own it. The strongest portfolios are often surprisingly simple. Not simplistic, but simple. Every exposure has a purpose. Every asset class plays a role. The investor understands how different components behave and why they are present inside the allocation. That clarity becomes extremely valuable during stressful environments because it supports discipline when emotions begin dominating the market narrative. Risk Management Is About Preparation, Not Prediction Many investors think risk management means predicting market crashes before they happen. In reality, prediction is only a very small part of effective portfolio management. Good risk management is mostly about preparation. Market stress rarely appears all at once. It usually develops gradually through smaller signals that become visible beneath the surface before volatility fully explodes. Credit conditions begin tightening. Market breadth weakens. Liquidity becomes less abundant. Leadership narrows. Prices start disconnecting from fundamentals. These signals matter because they help investors understand whether fragility inside the market is increasing. The objective is not to predict every correction perfectly. Nobody can do that consistently. The objective is to avoid being completely surprised when conditions deteriorate meaningfully. This approach changes the way portfolios are managed. Instead of reacting emotionally after volatility becomes obvious to everyone, disciplined investors gradually adjust exposure when evidence starts accumulating. Sometimes that means reducing concentration. Sometimes it means increasing liquidity. Sometimes it simply means becoming more
Portfolio Liquidity Management: Why Liquidity Is the Most Overlooked Strategic Asset
Ask most investors what their biggest portfolio risks are and they will describe equity market volatility, credit spreads, interest rate movements, or geopolitical events. Very few will mention liquidity. Yet time and again, across market cycles and financial crises, it is liquidity failure, not adverse price movements, that turns manageable difficulties into permanent losses. Portfolio liquidity management is one of the least glamorous and most important disciplines in investment practice, and its systematic neglect is one of the most consistent sources of avoidable financial damage. This article examines liquidity not as an afterthought or a residual balance but as a strategic asset that, when managed with intention, changes the character of a portfolio in fundamental ways. We will explore what liquidity actually means across different asset classes, how it behaves during market stress, why it creates optionality that has measurable economic value, and how to build a liquidity framework that serves both financial objectives and real-life needs. The argument throughout is not that investors should hold excessive cash but that liquidity should be a deliberate choice rather than whatever is left over after allocating to more exciting assets. What Portfolio Liquidity Actually Means Liquidity in investment portfolios refers to the ability to convert assets into cash quickly, at low cost, and at a price close to their current market value. This sounds straightforward, but each of those three conditions carries hidden complexity that becomes visible at precisely the moments when liquidity matters most. Speed matters because cash needs rarely arrive with advance notice. A business opportunity that requires capital deployment within days, a family emergency that demands immediate funds, a margin call that must be met by close of business: these are not exotic scenarios. They are routine features of complex financial lives. An investor who can only meet such needs over a period of weeks or months faces a genuine disadvantage relative to one who can act the same day. Cost matters because selling assets to raise cash is rarely free. Even in public markets, bid-ask spreads, market impact costs, and transaction fees erode the proceeds of forced liquidation. In private markets and illiquid asset classes, discount-to-appraisal sales can cost far more. An investor who must sell real estate, private equity, or hedge fund positions to raise cash may face discounts of ten to twenty percent or more from estimated fair value, particularly if the sale is time-sensitive. The true cost of illiquidity is not merely the inconvenience of waiting for proceeds but the capital destroyed when assets must be sold at unfavorable prices. Price stability matters because assets that appear liquid under normal conditions can become effectively illiquid when everyone wants to sell simultaneously. The bid-ask spread on high-yield bonds, for instance, might be thirty basis points in normal markets and three hundred basis points during a credit crisis. The number of buyers willing to purchase a secondary market stake in a private equity fund might be substantial in a benign environment and near-zero when credit is tightening and risk appetite has collapsed. Market liquidity, meaning the ability to transact at reasonable prices in reasonable size, is a conditional property that depends on broader financial conditions, not an inherent characteristic of the asset itself. The Strategic Value of Liquidity: Why It Is an Asset, Not a Cost The conventional view of liquidity treats it as a cost: you accept lower returns on liquid assets in exchange for the safety and flexibility they provide. This framing is not wrong, but it is incomplete. Liquidity has a positive, active value that goes beyond risk management. It creates optionality that can be converted into superior returns by investors who manage it with skill and discipline. Consider the investor who enters a market downturn with substantial liquidity. While less-prepared competitors are forced to sell assets to meet redemptions, cover margin calls, or fund operating needs, the liquidity-rich investor faces no such compulsion. Better: they can act as a buyer when asset prices have fallen to levels that offer exceptional value. History shows that the best buying opportunities in both public and private markets arise precisely when most investors are sellers, not buyers, which means they arise when liquidity is scarce. The investor who preserved liquidity specifically for this purpose can acquire assets at prices that generate above-average long-term returns, with the hindsight clarity that is only available to those who did not need to sell. This optionality has a precise economic value that can be estimated. Studies of market returns following severe drawdowns consistently show that investors who were able to increase equity allocation by twenty to thirty percent during major market bottoms earned returns over the subsequent three to five years that were ten to twenty percentage points higher than those who maintained static allocations. The liquidity that enabled these increases was not idle cash earning nothing: it was a call option on exceptional buying opportunities, exercisable at the investor’s discretion. Beyond market timing, liquidity creates flexibility to respond to real-life events that are entirely outside the financial markets. A family business facing an unexpected acquisition opportunity needs capital quickly. A family member developing a promising startup requires funding. A real estate acquisition at a compelling price emerges without warning. These opportunities are not available to investors who have no deployable capital. They accrue disproportionately to those who maintain liquidity not just as risk management but as active positioning. The framing of liquidity as a strategic asset also changes the way investors think about opportunity cost. When liquidity is viewed as a drag on returns, the natural tendency is to minimize it, always seeking ways to put the last increment of cash to work in higher-yielding investments. When liquidity is viewed as an asset with its own return characteristics, deriving from optionality and flexibility, the calculus changes. Holding thirty percent of a portfolio in liquid assets is not necessarily a decision to sacrifice return. It may be a decision to acquire a different kind of return: one that is
April 2026: slower markets, same discipline. Positive result
April 2026: slower markets, same discipline. Positive results. April confirmed what we already expected:markets are slowing down, uncertainty is high, and direction is not clear. After a subdued start to 2026, the month was characterised by:– low conviction across asset classes– geopolitical tensions– unclear signals from central banks– reduced risk appetite At the same time, some real economy segments are showing resilience —notably, the UAE real estate market, which is seeing renewed momentum. And for us, April also marks 1 month since the opening of our U.S. office.A key step in our international growth. Results – April 2026Forex Fund (Aggressive)+1.63% (April)+9.67% (YTD 2026)+74.70% since April 2024 Real Estate Fund+0.61% (April)+2.29% (YTD 2026)+16.37% since April 2024 Physical Gold15.80 Kg in custody€1.98M market value What matters– Even in a slow and uncertain market, results remain positive.– No aggressive positioning.– No forced trades. Just discipline, risk control, and consistency.We don’t try to outperform the market every month.We focus on protecting capital and building performance over time.Markets are in a transition phase.Patience is not optional. It’s required.IncomeCapitalIncomeCapitalManagementAssetManagementWealthManagementRiskManagementForexTradingealEstateInvestingGoldInvestmentCapitalProtectionAlternativeInvestmentsMacroEconomicsInvestmentStrategy
Political Risk Investing: How to Build a Disciplined Portfolio Strategy in an Uncertain World
Political Risk Investing: How Discipline Helps Investors Navigate Uncertainty Political risk is one of the most visible and emotionally charged forces in financial markets. Elections, policy changes, geopolitical tensions and unexpected government decisions can quickly dominate headlines and create the feeling that investors should react immediately. But not every political event deserves a portfolio adjustment. This is one of the most important lessons in political risk investing. The real issue is not whether something political has happened. Something is always happening. The real question is whether that event changes the economic conditions that matter for investors. At Income Capital Management, we believe political risk should be analysed through a disciplined framework rather than through emotion. Headlines can create anxiety, but portfolios should not be managed by anxiety. They should be managed through process, clarity and long term thinking. What Political Risk Really Means for Investors Political risk is often misunderstood because investors tend to focus on the event itself. An election result, a geopolitical escalation, a new regulation or a government announcement can all feel important in the moment. However, markets are not affected by events simply because they are visible. Markets are affected when events change expectations around growth, inflation, liquidity or capital flows. This distinction is essential. A political event may generate volatility for a few days without changing the long term direction of asset prices. Another event, less dramatic in the media, may change taxation, regulation, trade relationships or investor confidence in a way that has more durable consequences. Good political risk investing is not about reacting faster than everyone else. It is about understanding what actually matters. The Three Questions We Ask When we evaluate political risk, we do not start from the headline. We start from three practical questions. Does this event affect economic growth? Does it affect inflation? Does it affect capital flows? If the answer to these questions is no, the event may still create short term market noise, but it is less likely to justify a structural change in portfolio strategy. If the answer is yes, then the event deserves deeper analysis. Growth: The First Layer of Analysis Economic growth remains one of the key drivers of long term investment performance. Political decisions can influence growth through public spending, taxation, regulation, trade policy and business confidence. For example, a government that introduces investment incentives may support corporate activity. A policy shift that increases uncertainty for businesses may reduce capital expenditure. Trade restrictions can affect supply chains and corporate margins. The important point is not whether the policy is popular or unpopular. The important point is whether it changes the growth outlook in a meaningful way. If growth expectations change, asset allocation may need to be reviewed. Equities, credit, real estate and currencies may all respond differently depending on the direction and persistence of the change. Inflation: The Second Layer Inflation is often where political risk becomes more persistent. Energy policy, fiscal expansion, tariffs, public subsidies and trade restrictions can all influence inflation dynamics. This matters because inflation affects central bank decisions, and central bank decisions affect liquidity, rates, bonds, currencies and equity valuations. A temporary political shock may not change much. But a political decision that increases inflation pressure can have a much deeper effect. When inflation expectations move, portfolios often need to be reassessed. Duration risk, currency exposure, real assets and liquidity positioning all become more relevant. Capital Flows: The Signal Investors Should Not Ignore The third lens is capital flows. Markets ultimately move because capital moves. Investors allocate money where they see credibility, stability, opportunity and acceptable risk. When political uncertainty increases, capital may move away from a region, a currency or an asset class. This is why capital flows are often more useful than commentary. Opinions can be loud. Capital movement is more concrete. If investors begin reducing exposure to a market because political credibility is weakening, that matters. If a currency starts reflecting persistent capital outflows, that matters. If bond spreads widen because investors are demanding higher compensation for risk, that matters. Political risk becomes relevant when it begins to change where capital wants to go. Why Investors Often Overreact Most investors do not make mistakes because they lack information. They make mistakes because they react to information under pressure. A drawdown feels uncomfortable. A negative headline feels urgent. A geopolitical event creates fear. Someone else’s portfolio seems to be doing better. Suddenly, changing strategy feels like the responsible thing to do. Sometimes it is. Often it is not. Before changing strategy, the right question is simple: has your life changed, or only the market mood? If your objectives, time horizon, liquidity needs and risk capacity remain the same, a drastic change may do more harm than good. This does not mean portfolios should never change. They should. But changes should be based on structural reasons, not emotional triggers. Clarity, Discipline and Partnership In uncertain markets, investors need a framework they can trust. At Income Capital Management, we summarise our approach through three commitments: clarity, discipline and partnership. Clarity means investors should understand what they own and why they own it. A portfolio should not feel like a black box. Every allocation should have a purpose. Discipline means investment decisions should follow a documented process, not emotion. The market will always create pressure. A process helps prevent that pressure from becoming impulsive action. Partnership means the relationship with investors is not transactional. Wealth management is a journey that requires communication, context and trust over time. These principles guide how we think about Forex, Real Estate, Gold, Global Growth, High Yield and non-discretionary advisory. Different strategies have different roles, but the framework remains the same. Strategy Should Follow Life, Not Fear One of the most common reasons investors change strategy is discomfort. A market correction creates discomfort. A bad headline creates discomfort. A period of underperformance creates discomfort. But discomfort is not always a signal that something is wrong. Sometimes it is simply part of investing. The real
Cross Border Wealth Management for International Families
Cross Border Wealth Management for International Families Modern wealth is increasingly international. Families may live in one country, operate businesses in another, own property elsewhere and invest globally. Children may study abroad while future retirement plans involve a different jurisdiction entirely. This creates opportunity, but it also creates complexity. That is where cross border wealth management becomes essential. Without coordination, global families often face fragmented structures, duplicated costs, tax inefficiencies and unnecessary administrative stress. Why International Families Need a Different Approach Traditional financial planning is often designed for domestic situations. International families face different realities. They may hold multiple currencies, bank across jurisdictions, manage properties abroad and navigate separate legal systems. Income sources can come from salaries, businesses, dividends or rental assets located in different countries. This requires planning that connects all elements rather than treating each asset in isolation. Currency Exposure Matters Many cross border families underestimate currency risk. Wealth may be denominated in one currency while future liabilities exist in another. Education costs, property purchases or retirement spending can all be affected by exchange rate movements. A sound cross border wealth management framework considers these exposures carefully. Tax Efficiency and Clarity Different countries apply different tax rules to income, gains, inheritance and reporting obligations. Poor coordination can lead to inefficiency or avoidable confusion. Professional planning helps families structure assets with greater clarity and long term efficiency while remaining compliant with relevant regulations. Integrated Wealth Structures The strongest solutions are usually integrated rather than fragmented. Investments, liquidity, liabilities and family goals should work together inside one strategic framework. This allows better decision making and clearer reporting. Peace of Mind Has Value For many international families, complexity itself becomes a hidden cost. Too many advisors, too many disconnected accounts and too many uncoordinated decisions consume time and attention. Cross border wealth management aims to reduce that burden. Conclusion Global life should not create global confusion. With the right planning framework, international families can coordinate assets, manage risk and pursue long term goals with greater confidence. That is the real purpose of effective cross border wealth management. LinkedIn Post: Read original post
Investment Research Process: From Data to Better Decisions
Investment Research Process: From Data to Better Decisions Successful investing is rarely the result of instinct alone. Consistent results are more often built through discipline, evidence and a repeatable investment research process. In modern markets, information is everywhere. Prices move constantly, news flows never stop and opinions compete for attention every minute. The challenge is no longer access to data. The challenge is knowing how to use it. A professional investment research process creates structure in an environment that often feels chaotic. It helps investors distinguish between meaningful signals and temporary noise. Step One Begins with Relevant Data Good research starts by collecting the right inputs. These may include macroeconomic indicators, inflation trends, central bank policy, earnings expectations, valuations, sector rotation, liquidity conditions and sentiment measures. No single indicator explains markets on its own. Strong analysis comes from combining multiple sources into a coherent framework. Filtering Noise Matters Markets generate endless commentary. Many headlines create urgency without relevance. Reacting to every short term story often damages long term outcomes. A disciplined investment research process filters distractions and focuses on variables with proven relevance over time. This reduces emotional decisions and protects investors from chasing narratives that quickly disappear. Testing Assumptions Before Acting Every investment thesis should be challenged before capital is committed. What if inflation remains higher for longer. What if growth slows unexpectedly. What if credit conditions tighten. What if geopolitical events change sentiment rapidly. Scenario analysis improves resilience because it forces investors to think beyond the most comfortable outcome. Turning Research into Portfolio Action Research only becomes valuable when translated into decisions. This may mean adjusting allocations, reducing concentration, increasing liquidity or identifying attractive opportunities. For clients, this means every recommendation should have three foundations. A clear rationale, supporting evidence and an honest understanding of risk. Why Process Beats Prediction No research model can predict every market movement. That is not the objective. The real objective is to improve decision quality over time. Investors who rely on process rather than impulse usually make fewer costly mistakes. Conclusion A disciplined investment research process transforms raw information into practical judgment. It does not eliminate uncertainty, but it helps investors navigate uncertainty with more confidence, more consistency and better long term results. LinkedIn Post: Read original post
Why Human Advisors Still Matter in a Digital Wealth Management World
Why Human Financial Advisors Still Matter in a Digital World Technology has changed almost every aspect of modern finance. Investors now have access to real time data, automated reporting, portfolio dashboards, artificial intelligence tools and low cost execution platforms. Processes that once required hours can now be completed in seconds. Information that was once limited to institutions is now widely available to private investors around the world. This progress is real and valuable. Digital tools have improved transparency, reduced friction and expanded access to investment solutions. Yet despite all these advances, one reality remains constant. When decisions become personal, complex or emotionally significant, clients still seek a human financial advisor. The reason is simple. Wealth management is not only about numbers. It is also about judgment, priorities, family dynamics, uncertainty and trust. Software can calculate probabilities, but it cannot fully understand what matters most to a person at a critical stage of life. Why Technology Alone Is Not Enough Digital platforms are highly effective when the objective is efficiency. They can automate portfolio rebalancing, monitor performance, aggregate holdings and compare investment products. These are useful functions and they improve operational quality. However, many important financial decisions do not begin with spreadsheets. They begin with questions. Should I sell my business now or wait another year. How do I protect my family if markets become unstable. How should I prepare for retirement if my income is irregular. What is the best way to transfer wealth to the next generation. These questions involve context, timing and personal consequences. A human financial advisor helps translate technical possibilities into practical decisions. The Value of Human Judgment Markets are influenced by behavior as much as mathematics. Fear, overconfidence, herd mentality and short term reactions often shape outcomes. During periods of stress, many investors do not need more data. They need perspective. A trusted advisor provides discipline when emotions are strongest. This often means helping clients avoid costly mistakes such as panic selling, excessive concentration or chasing trends after they have already matured. Judgment also matters because every client situation is unique. Two people with the same level of wealth may need completely different strategies depending on family obligations, business exposure, liquidity needs or future plans. The Best Model Is Human Plus Technology The future of wealth management is not a choice between humans and machines. It is the intelligent combination of both. Technology should improve research, monitoring and execution. Advisors should focus on strategic thinking, communication and long term planning. When these strengths are combined, clients receive both precision and personal relevance. Trust Is Still the Core Asset In moments of uncertainty, trust becomes more valuable than convenience. Investors want to know that someone understands their position, communicates clearly and remains accountable. That is why the role of a human financial advisor remains powerful even in a digital age. Conclusion Technology will continue to reshape investing. Artificial intelligence, automation and analytics will become more advanced every year. But wealth decisions are still human decisions. For that reason, a skilled human financial advisor remains one of the most valuable assets an investor can have. LinkedIn Post: Read original post

