Position Sizing: The Decision That Comes Before the Trade
Position Sizing: The Decision That Comes Before the Trade Ask ten investors what makes a good trade and nine will talk about direction: where the market is going, and why. It is the glamorous half of investing, the part that fills interviews and headlines. Yet when portfolios fail, the autopsy rarely points to a wrong opinion about direction. It points to a defensible opinion held in indefensible size. Position sizing is the decision that comes before the trade: how much capital a single idea is allowed to put at risk, defined before the position exists and independent of how confident the idea feels. In professional currency management it is not an afterthought of the analysis. It is a policy, and in our experience it separates portfolios that survive their mistakes from portfolios that are defined by them. Why sizing errors hurt more than direction errors Every manager is wrong about direction regularly. That is not a flaw in the process; it is a property of markets. Decades of evidence show that even excellent currency strategies are wrong on a large share of their individual positions, and we have built our entire approach around that fact, as we described in why process beats prediction. Being wrong is survivable when the loss is bounded. What is not survivable is the combination of a wrong view and an oversized position, because losses do not scale linearly with recovery effort. A portfolio that loses ten percent needs roughly eleven percent to recover. One that loses forty percent needs sixty-seven. The arithmetic of drawdowns, which we examined in detail in our article on drawdown management, is the reason sizing is a survival discipline rather than an optimization exercise: the damage of being wrong grows faster than the benefit of being right. This is also why sizing cannot be left to conviction. Conviction is highest exactly where caution matters most, at the moments when a view feels obvious, the evidence seems overwhelming and the temptation to scale up is strongest. A sizing rule written in calm conditions exists precisely to overrule that feeling, because the feeling is not information about the future. It is information about the trader. What a sizing framework actually decides A disciplined framework answers three questions before any position is opened. The first is the maximum loss a single idea may inflict on the portfolio. Not the expected loss, and not the loss if things go mildly wrong: the loss if the position is stopped out at its predefined exit. That number is set as a fraction of capital small enough that no individual mistake, or short sequence of mistakes, threatens the portfolio’s ability to keep operating. The second is how positions combine. Two trades that look independent on a screen can be the same bet wearing different clothes: long one dollar pair and short another may both be, in substance, a single view on the dollar. Sizing limits that ignore correlation are limits in name only, which is why we treat this as part of the same discipline we described in our work on correlation risk: the unit being sized is the exposure, not the ticket. The third is how size responds to conditions. Volatility changes what a position of a given notional actually risks: the same size that is conservative in a quiet market is aggressive in a stressed one. A framework that holds risk constant must therefore let notional vary, trimming positions as volatility expands rather than discovering, after the fact, that the portfolio had grown without anyone adding a trade. Size as policy, not opinion The common thread in all three answers is that none of them depends on how good the idea looks. That is deliberate. Direction is an opinion, and opinions should compete, be challenged and sometimes be wrong. Size is a policy, and policies exist to be applied uniformly, especially when applying them is uncomfortable. In practice this means the sizing rule is decided at the level of the investment process, documented, and applied to every position without exception: not renegotiated trade by trade, not suspended for high-conviction ideas, not loosened after a good run. The moments when a manager most wants to make an exception are reliably the moments when the exception is most expensive, because overconfidence and risk concentration arrive together. There is a quieter benefit as well. When size is fixed by rule, the quality of decisions becomes measurable. A portfolio where every idea risks a comparable fraction of capital produces a track record that reflects judgment rather than courage, and errors become data instead of events. Over the many decisions that make up a year of currency management, that feedback loop is worth more than any single trade. The question that protects the next hundred decisions The practical test of a sizing discipline is a single question, asked before every trade: how much is this position allowed to lose if it is wrong? Not how much it should make, and not how likely it is to work. If the answer is a number fixed in advance by policy, sizing is doing its job. If the answer depends on how the idea feels, the portfolio is one streak of confidence away from a problem. Direction decides whether a trade makes money. Size decides whether the portfolio survives being wrong long enough for the process to work. Of the two decisions, only one can be fully controlled in advance, and professional management is, above all, the discipline of controlling what can be controlled. This article is provided for informational and educational purposes only. It does not constitute investment advice, an offer, or a solicitation to invest in any product or service. Income Capital Management s.r.o. is registered under §15 of the Czech Act on Investment Companies and Investment Funds (ZISIF). Past performance is not indicative of future results. Investing involves risk, including the possible loss of capital.
Why Execution Quality Matters in Currency Markets
Why Execution Quality Matters in Currency Markets Take two portfolio managers with the same idea, the same entry level, the same size and the same exit. On paper their trades are identical. In practice their results are not, because between the decision and the account statement sits execution: the spread paid, the slippage absorbed, the moment chosen, the counterparty used. In most markets this difference is treated as rounding. In currency markets, where positions are large, trades are frequent and margins are structural rather than spectacular, it is nothing of the sort. At TradeTech FX Europe 2026 in Amsterdam, which we covered in detail in our conference review, one theme kept surfacing across sessions and conversations: execution quality is becoming a competitive advantage in institutional currency markets, not an operational detail. This article explains what that phrase actually means, why the industry has reached that conclusion, and what disciplined execution looks like in practice. What execution quality actually is Execution quality is the difference between the price a strategy assumes and the price a portfolio actually gets. It is made of components that are individually small and easy to ignore. The first is the spread, the visible cost of crossing from bid to offer. The second is slippage, the drift between the price observed when the decision is made and the price at which the order fills. The third is market impact, the way an order itself moves the price against the trader, which grows with size and shrinks with patience. The fourth is the reliability of the fill: rejection rates, requotes, and the behavior of a counterparty in the seconds when markets move fastest. None of these appears as a line item on a performance report. All of them are paid. That is what makes execution quality unusual among portfolio costs: it is real, recurring and largely invisible unless it is deliberately measured. Why small numbers become large ones The arithmetic is unforgiving. A cost of a fraction of a pip per trade sounds negligible, and on a single transaction it is. But currency portfolios trade continuously: positions are opened, adjusted, hedged and closed through the year, and in leveraged structures the notional traded is a multiple of the capital deployed. Multiply a tiny per-trade cost by thousands of trades on amplified notional and the result is no longer a rounding error. It is a permanent drag that compounds against the portfolio with the same patience that returns compound for it. This is also why execution quality cannot be evaluated by anecdote. A trader remembers the fill that went wrong, not the accumulated centimeters lost on the fills that went slightly worse than they should have. Only systematic measurement, what the industry calls transaction cost analysis, makes the invisible visible: comparing every fill against the prevailing market at the moment of the decision, aggregating the differences, and attributing them to venues, counterparties, times of day and order types. Why institutions now treat it as an edge For years, execution was considered plumbing: necessary, unglamorous, delegated. What changed, and what Amsterdam made explicit, is the recognition that in a market where genuine predictive edges are rare and fragile, the edges that persist are structural. Nobody can guarantee being right about direction more often than competitors. A firm can, however, systematically pay less to implement its decisions than competitors pay to implement theirs, and that advantage does not decay when it becomes known. There is a second reason, and it connects directly to a subject we have examined before: liquidity. Execution quality is where liquidity risk stops being abstract and becomes a number. Our article on what happens when liquidity disappears argued that liquidity measured in calm conditions is a promise rather than a property. Execution data is how that promise is tested. Spreads that widen tenfold in stress, counterparties that reject orders exactly when hedging matters most, depth that evaporates around data releases: these show up first, and sometimes only, in execution records. A firm that measures its execution is also, whether it intends to or not, continuously auditing its access to liquidity. What disciplined execution looks like Good execution is not heroic trading. It is a set of unspectacular habits applied without exception. It starts with measurement, because what is not measured cannot be managed and will quietly deteriorate. It continues with counterparty and venue selection reviewed against evidence rather than relationships: who actually provides depth when conditions tighten, not who provides it when nothing is happening. It includes decisions about order size and timing, trading in a way that respects the market’s capacity to absorb an order instead of forcing it. And it includes knowing when not to trade at all, because the most expensive fills cluster in the moments when liquidity is thinnest and urgency is highest. Readers of this blog will recognize the pattern. This is the same logic we described in why process beats prediction, applied one layer deeper in the machinery: rules designed in calm conditions, applied in all conditions, precisely because discretion is least reliable when pressure is greatest. The quiet part of performance Execution quality will never be the exciting part of currency management. No investor asks about slippage in a first meeting, and no headline is written about a spread paid well. But over any meaningful horizon, the portfolios that endure are the ones that stop leaking, and execution is one of the few places where a manager’s discipline translates into basis points with near certainty rather than probability. That is why we treat execution as part of the investment process itself, measured and reviewed like any other risk, and why we found it significant that the institutional market has publicly arrived at the same view. When an industry’s most sophisticated participants start competing on how well they implement decisions rather than only on which decisions they make, it says something about where durable advantages actually live. This article expands on Nicola Pinchi’s reflections following TradeTech FX Europe 2026. This
What TradeTech FX Europe 2026 Told Us About Institutional Currency Markets
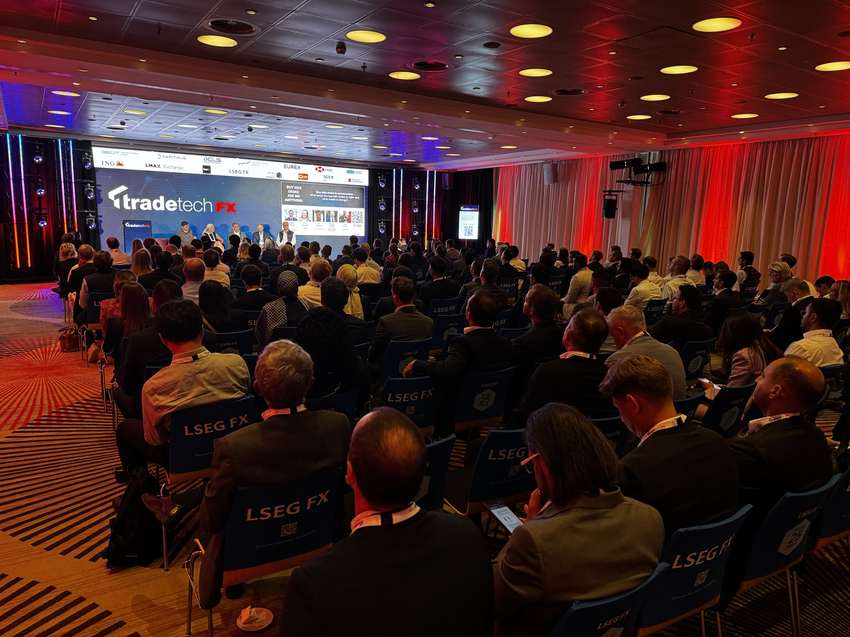
What TradeTech FX Europe 2026 Told Us About Institutional Currency Markets In mid-September, Income Capital Management attended TradeTech FX Europe 2026 in Amsterdam, Europe’s largest gathering of the institutional currency market: three days at the Mövenpick Hotel and ijVENUES, around eight hundred participants, more than thirty sessions and ninety speakers drawn from asset managers, hedge funds, pension funds, banks, corporate treasuries and technology providers. We attend events like this for a simple reason. Currency markets are decentralized by nature; there is no single exchange floor where the industry becomes visible. Once a year, this conference comes close, and three days of sessions and conversations compress more information about where institutional FX is heading than months of reading. This article is what we brought home: the three themes that dominated the event, and what they confirm about how currency portfolios should be run. Liquidity was the center of gravity If the 2026 edition had one center of gravity, it was liquidity: how to access it, what it costs, and how its structure keeps changing. Session after session returned to the same cluster of questions, from liquidity access and credit constraints to the mechanics of FX swaps and the way market structure keeps fragmenting across venues and bilateral relationships. The tone of those discussions is worth reporting, because it has shifted. Liquidity is no longer treated as a background condition that execution desks worry about; it is discussed as a first-order portfolio risk, priced, planned and stress-dependent. That matches the position we have argued on this blog for months, most directly in our article on what happens when liquidity disappears: liquidity measured in calm conditions is a promise, not a property, and the institutions that treat it as a design input rather than an assumption are the ones that keep their options in stressed markets. Our own conversations on the floor, with prime services desks and institutional liquidity providers, pointed the same way. The questions that matter in those relationships are structural: depth under stress, credit terms, what happens to pricing when volatility arrives. The industry is converging on the view that access to robust liquidity is part of a fund’s architecture, as much as its strategy is. AI moved from promise to plumbing The second theme was artificial intelligence, and the interesting part was not its presence, which was expected, but its tone. The conversation has moved from prediction to plumbing: the practical application of AI in pre-trade analytics, workflow automation, execution quality and data infrastructure, rather than grand claims about machines that forecast markets. That evolution deserves to be noticed, because it quietly concedes a point this blog has made repeatedly. The durable edge in currency markets does not come from knowing what happens next; decades of evidence say nobody reliably does, as we documented in our article on why process beats prediction. What AI is actually being deployed to do, in the institutions presenting at Amsterdam, is make the process better: faster analysis before a trade, cleaner execution during it, sharper measurement after it. The technology is upgrading the machinery around decisions, not replacing the discipline that decisions require. A tool that strengthens a process is valuable; a tool sold as a substitute for one is a warning sign, and the institutional market seems to have learned the difference. Geopolitics, and the humility it is teaching The third thread running through the agenda was geopolitical uncertainty and its impact on trading strategies: policy divergence, fragmenting trade relationships, and the recognition that macro regimes are shifting faster than models built on the last decade can track. What struck us was not the analysis itself but the posture behind it. Very few speakers offered confident forecasts. The prevailing question had become the one we consider correct: not “what will happen” but “how do we build portfolios that survive whichever version happens.” Scenario thinking, hedging frameworks and regime-aware risk limits dominated the discussion, which is the institutional vocabulary for something we wrote about recently in preparing portfolios for the final quarter: preparation over prediction, structure over sentiment. When the most sophisticated participants in a market collectively lower their confidence in forecasting and raise their investment in resilience, that is information in itself. What three days in Amsterdam confirm Stepping back, the three themes are one theme. Liquidity as architecture, AI as process infrastructure, geopolitics answered with preparation rather than conviction: each is the institutional market arriving, from a different direction, at the same conclusion. Outcomes in currency markets are decided by structure, and the industry’s best participants are investing in structure. For a firm like ours, the value of being in that room is twofold. The conversations themselves, with the banks, providers and managers who make up the market’s infrastructure, are how operating relationships stay current. And the aggregate signal, what eight hundred professionals collectively choose to discuss for three days, is the closest thing currency markets offer to a statement of direction. This year’s statement was clear, and it happens to describe the way we already work. We left Amsterdam with new contacts, several ideas worth testing, and one conviction reinforced: the fundamentals of professional currency management do not change with the headlines. Structure, liquidity, discipline and process were the agenda in Amsterdam, and they are the agenda every other week of the year as well. This article follows Nicola Pinchi’s participation at TradeTech FX Europe 2026 and expands on his LinkedIn post ahead of the event. This article is provided for informational and educational purposes only. It does not constitute investment advice, an offer, or a solicitation to invest in any product or service. Income Capital Management s.r.o. is registered under §15 of the Czech Act on Investment Companies and Investment Funds (ZISIF). Past performance is not indicative of future results. Investing involves risk, including the possible loss of capital.
The Structure Behind a Professional Forex Fund
The Structure Behind a Professional Forex Fund Ask a retail trader what makes a good forex operation and the answer will usually involve signals, timing, or a proprietary method for reading the market. Ask an institutional allocator the same question and the answer changes completely: they will talk about limits, processes, and what happens when things go wrong. That difference in perspective is the subject of this article. A professional forex fund structure is not built on trading signals. It is built on risk frameworks, exposure limits, drawdown control, and systematic decision rules, and the quality of that structure determines outcomes more reliably than the quality of any individual trade. Why the currency market rewards structure over instinct The foreign exchange market is the largest and most liquid market in the world. According to the Bank for International Settlements, turnover in FX markets averaged 9.5 trillion US dollars per day in April 2025. That depth is a genuine advantage for a professionally managed fund: positions can be built and unwound at scale without moving prices, and liquidity remains available even when other markets thin out. The same characteristics, however, punish improvisation. Currency prices respond to interest rate differentials, macro data, central bank policy, and flows that no participant fully observes. Leverage is widely available and cuts in both directions. A market this deep and this fast does not forgive structural weaknesses; it finds them. This is why the operations that survive across market regimes are rarely the ones with the best market calls. They are the ones where every decision that matters was made before the market forced it. The mandate: deciding what the fund does not do Structure begins with the mandate, and a serious mandate is defined as much by exclusions as by objectives. Which currency pairs are in scope and which are not. Which instruments the strategy may use. What maximum leverage is permitted, under which conditions. What the fund explicitly will not do, regardless of how attractive an opportunity appears. The exclusions matter because pressure to deviate always arrives dressed as opportunity. A strategy drifts one exception at a time: an unusual pair because the setup looked compelling, extra leverage because conviction was high, a new instrument because a competitor was using it. Each deviation seems reasonable in isolation. Together they produce a portfolio whose risk profile no longer matches anything the investor agreed to. A written mandate, enforced without exceptions, is the first and cheapest control a fund can have. Exposure limits: the core of a forex fund structure Inside the mandate sits the risk framework, and its core instrument is the exposure limit. A professional forex fund structure defines, in advance, how much exposure is acceptable at several levels at once: per currency pair, per position, per directional theme, and for the portfolio in aggregate. The layering is deliberate. Individual position limits prevent any single trade from dominating outcomes. Aggregate limits prevent a collection of individually reasonable positions from quietly becoming one large bet. Thematic limits address the subtler problem of correlated exposure: three positions in different pairs can amount to a single view on the dollar, and a framework that only counts positions will miss it. This is the same correlation logic that governs portfolio construction more broadly, which we examined in our article on correlation risk and diversification: what matters is not how many exposures you hold, but how they behave together under stress. Position sizing completes the framework. Size is a function of the limit structure and the volatility of the pair, not of conviction. Conviction-based sizing grows with confidence, and confidence grows with recent success, which is precisely how risk concentrates at the worst possible moment. Drawdown control: the rules that act before judgment does Every strategy, without exception, goes through periods of loss. What distinguishes a structured fund is that the response to those periods is specified in advance and executes independently of anyone’s mood. Drawdown control operates on thresholds. At defined levels of loss, exposure is reduced according to pre-set rules. At deeper levels, the strategy de-risks further or pauses entirely while the process is reviewed. The thresholds and the responses are written down before the first trade, because a drawdown is the single worst environment in which to design a response: judgment is impaired, incentives push toward recovery bets, and every instinct argues for one more exception. The arithmetic behind drawdown discipline is unforgiving and worth restating. A 20% loss requires a 25% gain to recover; a 50% loss requires 100%. Deep drawdowns cost time as much as money, and they push strategies toward the forced decisions that convert temporary losses into permanent ones. Keeping drawdowns shallow is not caution for its own sake. It is what makes long-term compounding arithmetically possible. Systematic decision rules: removing the moment from the decision The fourth pillar is the decision framework: the rules that govern how positions are opened, managed, and closed. In a structured fund, entries and exits follow defined criteria. Reviews happen on a schedule, not when someone feels the need. Changes to the process itself go through a deliberate procedure rather than being improvised mid-drawdown. None of this eliminates judgment. Markets change, and a process that never evolves is a different kind of risk. The point is that judgment operates on the process, calmly and on schedule, rather than inside individual trades under pressure. The behavioral case for this separation is one we made at length in our article on investment discipline: most damage in markets comes not from lack of knowledge but from inconsistency in execution, and consistency cannot be left to willpower. It has to be engineered. Consistency across regimes, not performance spikes The objective of all this structure is easy to misread. It is not to maximize returns in any given month. It is to produce behavior that remains consistent across market regimes: trending and ranging markets, high and low volatility, calm conditions and stressed ones. Performance spikes are cheap to generate. Concentrate

