How I Explain Investment Risk to Non-Finance People | Income Capital Management
How I Explain Investment Risk to Non-Finance People By Paolo Volpicelli — Income Capital Management Risk is the most important concept in finance. It is also the one most consistently explained badly. When investment professionals talk about risk with each other, they speak in the language of standard deviations, Value at Risk, Sharpe ratios, and maximum drawdown percentages. This language is precise and useful — among professionals. But when a surgeon, a family business owner, a lawyer, or a parent sits across the table from you and asks “is this safe?”, that vocabulary does not just fail to help. It actively gets in the way. Over years of working with clients from backgrounds far outside finance at Income Capital Management, I have learned that the goal of a risk conversation is not to educate people about financial theory. It is to connect what the numbers mean to what the person actually feels, needs, and fears. That requires a completely different approach — and a completely different set of questions. Investment Risk Explained: Start With Questions, Not Definitions The single most effective tool I have found for explaining investment risk is not a chart, not a formula, and not a slide deck. It is a question. Specifically, three questions that I ask every new client before we discuss a single number: “How would you feel if your portfolio dropped 15% in one year?” Not: what is your risk tolerance on a scale of one to ten. Not: are you a conservative, balanced, or aggressive investor. Those abstract categories produce abstract answers that do not survive contact with a real drawdown. Asking how someone would feel — not what they would think — opens a completely different conversation. Some people say “I would be worried but I would hold on.” Others say “I would not be able to sleep.” Both answers are equally valid, and both tell me something essential about how a portfolio needs to be designed. “How stable is your income?” A surgeon with a long, established practice has very different risk capacity than a freelancer whose revenues swing significantly from year to year, even if both have the same amount to invest. Risk capacity — the financial ability to absorb losses without being forced to sell at the wrong moment — is as important as risk tolerance, and it is almost always determined by the stability and predictability of the client’s income and obligations outside the portfolio. “What is non-negotiable for your family?” Every client has a financial floor — a level below which their lifestyle, their family’s security, or their business cannot function. Identifying that floor explicitly is what allows us to design a portfolio that can pursue growth or income above it while protecting the capital that is genuinely irreplaceable. This question makes the abstract concept of capital preservation concrete and personal. From Emotions to Numbers: Translating Risk Into Reality Once these questions have been answered, something important has happened: the client has connected their emotional reality to the financial decisions ahead. At that point, introducing technical concepts becomes not only possible but natural — because they now have a personal frame of reference to attach them to. Volatility is the measure of how much a portfolio value fluctuates over time. For most non-finance clients, this becomes meaningful the moment you link it back to their first answer: “a portfolio with this level of volatility might drop 15% in a bad year, but it has historically recovered within two to three years.” Suddenly volatility is not an abstract statistical concept — it is the price of participation in a strategy that delivers a specific long-term return. Drawdown — the peak-to-trough decline in portfolio value — is the concept that tends to land hardest when clients experience it for the first time. The reason is that a 20% loss requires a 25% gain just to break even: the mathematics of loss are asymmetric, and most people have not internalised this intuitively. I explain this not with formulas but with simple examples: “if you invest 100 and it drops to 80, you need to grow from 80 back to 100, which is a 25% return from that lower base.” That single insight changes how people think about managing the downside. Liquidity is perhaps the risk that surprises non-finance clients most when they encounter it in practice. The idea that an investment might be performing well but simply not be accessible when needed — because of redemption windows, lock-up periods, or illiquid market conditions — is counterintuitive to people accustomed to a current account or a savings product. I explain liquidity through the lens of their third question: if something non-negotiable for your family required €50,000 in the next three months, could we access it without disrupting the rest of the strategy? That question makes liquidity risk immediately real. Time horizon is the variable that ties everything else together. A short time horizon transforms risks that are perfectly manageable over ten years into genuine threats — because there is no time for recovery. Aligning the investment strategy with the client’s actual time horizon for each pool of capital is one of the most impactful decisions in portfolio construction, and one that only becomes possible when the client has been genuinely honest about what different parts of their wealth are for. When People Understand Risk, Returns Become a Consequence The most important shift I have observed in clients who have gone through this kind of risk conversation is not technical. It is psychological. Before the conversation, most people approach investing primarily through the lens of returns: what will this make me? After a genuine, grounded risk conversation, the frame changes: what can I hold through, and what will that enable over time? This shift matters enormously for long-term investment outcomes. Investors who understand the risks they are taking — and who have chosen those risks deliberately, in line with their real emotional and financial capacity — are far more likely
Physical Gold Investment: More Than Just a Safe Haven | Income Capital Management
Physical Gold Investment: More Than Just a Safe Haven By Paolo Volpicelli — Income Capital Management Ask most investors what gold is for, and you will hear the same answer: it is something you hold when everything else is going wrong. A crisis asset. A last resort. The thing you turn to when currencies collapse, markets implode, or geopolitical risk spikes beyond what conventional portfolios can absorb. This view of gold is not wrong — but it is incomplete, and for many investors it leads to a systematic underuse of one of the most versatile assets available in modern portfolio construction. Physical gold has been a store of value for thousands of years. That track record is real and it matters. But for today’s investor, the question is not whether gold has preserved wealth across centuries. The question is whether it belongs in your portfolio right now — in what form, in what size, and connected to what overall strategy. At Income Capital Management, our answer is yes — and the reasoning goes well beyond the traditional safe-haven narrative. Why Physical Gold Investment Still Makes Sense Gold has outlasted every fiat currency ever created. That single fact carries more weight than any quantitative model, because it reflects something fundamental about the nature of the asset: it cannot be printed, debased, or defaulted on. In a world where central bank balance sheets have expanded to historic proportions and sovereign debt levels in major economies continue to rise, this property is not merely historical — it is structurally relevant. But the case for physical gold investment in a modern portfolio rests on more than distrust of paper money. Gold has several concrete portfolio characteristics that make it genuinely useful as an active strategic allocation rather than a passive emergency reserve. First, gold has a low and sometimes negative correlation with equities and credit assets during periods of acute market stress — precisely when diversification from traditional assets matters most. When equity markets sell off sharply and credit spreads widen, gold often moves in the opposite direction, providing a natural offset to losses elsewhere in the portfolio. This is not a coincidence; it reflects gold’s role as a preferred destination for capital during risk-off regimes. Second, gold has historically maintained its purchasing power over long periods relative to goods and services. While it is not a perfect inflation hedge in the short term — gold can underperform for extended periods even when inflation is elevated — over multi-decade horizons it has consistently preserved real value in ways that nominal bonds and cash cannot. For investors with long time horizons and a concern about the erosion of purchasing power, this is a meaningful contribution. Third, and perhaps most importantly for portfolio construction purposes, gold provides psychological stability. During periods of severe market stress, investors with a meaningful gold allocation tend to behave more rationally — because they can see a portion of their wealth holding its value or appreciating while other assets fall. This behavioural dimension is underrated in academic portfolio theory but critical in practice. An investor who stays invested through a crash because their gold allocation is cushioning the drawdown will almost always outperform one who sells everything at the bottom. Allocated Holdings: Why Physical Matters Not all gold exposure is equivalent, and the distinction between physical gold and paper gold is one that every serious investor should understand clearly. Gold ETFs, futures, and certificates offer convenient price exposure to gold — but they are financial instruments, not the metal itself. In a genuine tail risk scenario — the kind of systemic stress that gold is most valued for hedging against — the performance of these instruments depends on the functioning of the financial infrastructure that underlies them: clearing houses, counterparties, custodians, and markets. In extreme scenarios, that infrastructure is precisely what may be under strain. Allocated physical gold holdings are different. When gold is held in allocated form, specific bars or coins are legally assigned to the investor and segregated from the custodian’s own assets. The investor owns the physical metal — not a claim on it, not exposure to it, but the metal itself — held on their behalf in a professional custody facility with independent auditing and transparent pricing. Through our Physical Gold solution at Income Capital Management, clients access exactly this structure: allocated holdings with professional custody, independently verified, fully transparent in pricing, and fully integrated into their broader portfolio reporting. The gold they hold is real, auditable, and legally theirs — with none of the counterparty risk that attaches to paper alternatives. Sizing and Integration: The Key to Making Gold Work The most common mistake investors make with gold is not holding it — it is holding it wrong. Specifically, treating it as an isolated position rather than a deliberately sized component of an integrated strategy. Too little gold — a token 1% or 2% allocation added almost as an afterthought — provides negligible diversification benefit. It is large enough to require management attention but too small to meaningfully offset losses in other assets during a crisis. Too much gold — a concentrated 20% or 30% allocation driven by macro anxiety — creates a different problem: gold generates no income, pays no dividend, and produces no cash flow. An overweight gold position is a bet on continued monetary instability, and while that bet may eventually pay off, it extracts a significant opportunity cost in the interim. The right allocation depends on the client’s broader portfolio, their income requirements, their time horizon, and their specific exposure to the risks that gold is most effective at hedging. For most diversified portfolios, a strategic allocation in the range of 5% to 10% tends to capture the meaningful diversification and tail-risk hedging benefits of gold without sacrificing too much in terms of income generation or growth potential. Crucially, this allocation needs to be connected to the overall strategy — not treated as a standalone bet. In our framework, the Physical
VPS Monitoring and Hosting Reliability: Why Infrastructure Providers Must Do Better
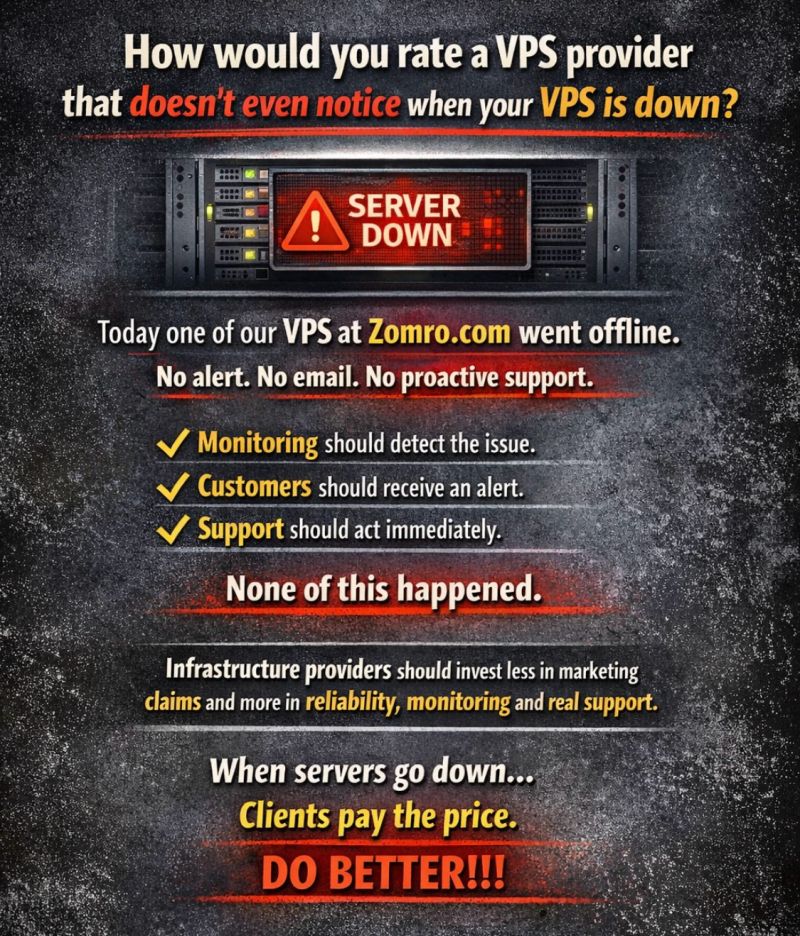
VPS Monitoring and Hosting Reliability: Why Infrastructure Providers Must Do Better Modern businesses depend on digital infrastructure. Websites, trading systems, financial dashboards, APIs, and internal tools rely on servers running continuously in the background. In this environment, VPS hosting providers play a critical role in ensuring that services remain online and accessible. Yet one of the most basic expectations of infrastructure providers is still frequently overlooked: reliable monitoring and proactive support when a server goes down. Recently, one of our VPS servers hosted with Zomro.com went offline. The issue itself was not extraordinary — hardware failures, network interruptions and system crashes are realities of operating digital infrastructure. What was surprising, however, was something else entirely: no alert, no email notification, and no proactive response from the hosting provider. For companies that sell remote infrastructure services, this should be the absolute minimum standard. The Minimum Standard for VPS Infrastructure Providers Professional infrastructure providers are expected to deliver more than server rental. They are responsible for maintaining systems that businesses depend on for their daily operations. At the very least, three elements should always be present in any VPS hosting environment: Automated uptime monitoring Immediate alerts when servers become unavailable Rapid response support teams capable of investigating outages Without these basic safeguards, customers are left discovering failures themselves — often after websites, applications or financial services have already stopped working. Why Monitoring Is Not Optional In the world of cloud infrastructure and modern DevOps environments, monitoring is not a luxury feature. It is a fundamental requirement. Monitoring systems track key indicators such as: Server uptime Network availability CPU load Memory usage Disk health Application responsiveness When any of these metrics cross critical thresholds, alerts should be triggered automatically. This allows infrastructure teams to respond before the issue escalates into a full outage. Most modern hosting providers claim to offer monitoring, but the quality and reliability of these systems varies widely. In practice, many providers rely on reactive support models where customers are expected to report problems themselves. This approach may reduce operational costs, but it shifts risk entirely onto the customer. The Cost of Downtime Server downtime is not merely an inconvenience. For many businesses, it directly translates into lost revenue, damaged reputation, and operational disruption. Consider the consequences when critical infrastructure fails unexpectedly: Websites become inaccessible Financial platforms stop processing transactions APIs break integrations with external services Client dashboards go offline Internal tools stop functioning Even a short interruption can cascade into larger operational problems. This is why professional hosting providers invest heavily in site reliability engineering (SRE), redundancy, and monitoring systems. What Good VPS Providers Actually Do High-quality hosting companies operate under a different philosophy: they treat infrastructure reliability as a core product feature. The best VPS providers implement: Real-time monitoring systems Automatic outage detection Multi-channel alerting (email, SMS, dashboard notifications) 24/7 support teams incident response procedures post-incident analysis In well-run infrastructure environments, outages are not hidden problems waiting to be discovered. They are events that trigger immediate investigation and communication. The Responsibility of Infrastructure Providers Hosting providers operate the backbone of the modern internet. From startups to global enterprises, organizations depend on reliable infrastructure for everything from financial services to e-commerce. Because of this responsibility, infrastructure companies should invest less in marketing claims and more in the systems that actually matter: reliability engineering monitoring infrastructure support operations network resilience When servers go down, clients are the ones who pay the price. The impact is felt not only technically but financially and operationally. Why Independent Monitoring Is Essential One lesson every experienced infrastructure user eventually learns is this: never rely solely on your hosting provider to detect outages. Independent monitoring tools such as UptimeRobot, Better Uptime, Pingdom, and other uptime monitoring services allow organizations to track server availability from external locations. These tools can provide: external uptime verification independent alerting performance history downtime reports For businesses running critical systems, independent monitoring should always be part of the infrastructure strategy. Infrastructure Reliability Is the Real Product The hosting market is highly competitive, and many providers focus their messaging on low prices, high performance hardware, or unlimited bandwidth. However, the true product of a hosting company is not disk space or CPU power. It is reliability. Clients do not purchase servers simply to own infrastructure. They purchase the assurance that their digital systems will remain operational when needed. Without reliable monitoring and responsive support, that assurance disappears. Final Thoughts Server outages will always happen. Hardware fails, networks experience disruptions, and software crashes. What separates professional infrastructure providers from mediocre ones is not the absence of problems, but how quickly those problems are detected and addressed. Monitoring should detect the issue. Customers should receive alerts. Support teams should respond immediately. These are not premium features. They are the foundation of modern infrastructure services. Because when servers go down, the consequences extend far beyond a single machine. And infrastructure providers should always remember that. Original LinkedIn Post: Read the original discussion on LinkedIn
ESG Beyond the Label: How Professional Investors Evaluate Sustainable Companies
ESG Beyond the Label: What I Really Look At Environmental, Social and Governance investing—commonly referred to as ESG—has become one of the most widely discussed topics in modern finance. Over the past decade, asset managers, institutional investors and financial advisors have increasingly incorporated ESG considerations into portfolio construction. For many investors, ESG represents the possibility of combining financial performance with responsible capital allocation. However, as ESG investing has gained popularity, another phenomenon has emerged alongside it: the rapid proliferation of labels, certifications and marketing claims. Many companies and financial products now highlight their ESG credentials prominently, often through logos, ratings or sustainability statements. At first glance, these labels may appear reassuring. They suggest that environmental responsibility, social impact and governance standards have already been evaluated. For investors seeking sustainable opportunities, such indicators seem to simplify the decision-making process. Yet the reality is more complex. Not all ESG labels are created equal. In fact, one of the greatest risks in ESG investing is the assumption that a label automatically guarantees meaningful sustainability practices. In many cases, the visible symbols attached to financial products represent only a partial assessment of how a company truly operates. This is why professional investors must go far beyond surface-level classifications. ESG is not a sticker placed on a company. It is a framework for understanding how businesses create long-term value while managing environmental, social and governance risks. The Rise of ESG Investing The growth of ESG investing reflects a broader transformation in how investors think about capital allocation. Financial markets are increasingly aware that long-term performance cannot be separated from environmental responsibility, ethical governance and social stability. Companies operate within complex ecosystems that include employees, suppliers, communities and regulators. Decisions made within these ecosystems influence not only financial outcomes but also broader societal and environmental conditions. Investors have therefore begun to recognize that sustainable business practices are often closely linked to long-term financial resilience. Organizations that manage environmental risks responsibly, maintain transparent governance structures and foster positive relationships with stakeholders tend to demonstrate stronger operational stability over time. This insight has driven the rapid expansion of ESG-focused funds and investment strategies across global financial markets. The Problem with ESG Labels Despite its positive intentions, the ESG movement has also created challenges. One of the most widely discussed concerns is the risk of “greenwashing.” Greenwashing occurs when companies or financial products promote sustainability claims that are not fully supported by their actual business practices. Marketing materials may emphasize isolated initiatives while overlooking broader operational realities. For example, a company may highlight its use of renewable energy in certain facilities while maintaining environmentally harmful practices elsewhere within its supply chain. Similarly, an investment product may receive an ESG rating based on limited criteria that do not fully capture governance risks or social impact. These inconsistencies illustrate why labels alone cannot serve as the foundation for responsible investment decisions. Going Deeper: Real ESG Analysis Professional ESG evaluation requires a far more comprehensive approach. Rather than relying solely on external ratings, investors must examine how companies operate internally and how their practices influence long-term value creation. This analysis typically involves several key dimensions. Employee Treatment and Corporate Culture The social dimension of ESG begins with how companies treat their employees. Workplace conditions, employee engagement and organizational culture influence productivity, innovation and long-term business sustainability. Companies that invest in workforce development, promote fair labor practices and maintain transparent internal communication tend to demonstrate stronger resilience during economic challenges. Conversely, organizations that neglect employee well-being often experience higher turnover rates, reputational damage and operational instability. Supply Chain Responsibility Another critical factor in ESG analysis is supply chain management. Global companies frequently depend on complex supplier networks that span multiple countries and regulatory environments. Responsible supply chain governance ensures that environmental standards, labor rights and ethical sourcing practices are respected throughout the production process. Investors must therefore evaluate not only the company itself but also the behavior of its partners and suppliers. This broader perspective helps identify risks that may not be visible in corporate sustainability reports. Governance and Risk Oversight Corporate governance represents one of the most important components of ESG analysis. Strong governance structures provide oversight, accountability and transparency in corporate decision-making. Investors examine factors such as board independence, executive compensation alignment, shareholder rights and risk management procedures. Companies with robust governance frameworks are more likely to maintain financial discipline and respond effectively to emerging challenges. Weak governance, on the other hand, can expose investors to strategic mismanagement and reputational risks. Transparency and Reporting Quality Transparency is another key indicator of ESG credibility. Companies that provide detailed, verifiable disclosures regarding environmental impact, social policies and governance practices allow investors to conduct meaningful analysis. Transparent reporting demonstrates confidence and accountability. In contrast, vague sustainability statements or incomplete disclosures may indicate that ESG commitments are more symbolic than operational. ESG as a Driver of Value Creation Perhaps the most important question in ESG analysis is whether sustainability initiatives genuinely contribute to long-term value creation. Responsible business practices should not be viewed merely as ethical obligations. When implemented effectively, they often enhance financial performance. For example, energy efficiency improvements can reduce operational costs. Strong governance structures can prevent costly legal disputes. Positive employee relations can improve productivity and innovation. In these cases, ESG considerations align naturally with investor interests. The objective is not to choose between impact and returns. The objective is to identify businesses where responsible practices strengthen both. Integrating ESG into Investment Strategy At Income Capital Management, ESG analysis forms part of a broader investment framework designed to evaluate long-term resilience. This framework combines fundamental analysis, macroeconomic evaluation and sector-level research to identify companies capable of sustainable growth. Rather than excluding entire industries based on simplified classifications, the focus remains on understanding how individual companies operate within their environments. This approach allows investors to identify organizations that genuinely integrate sustainability into their business models. Impact and Returns: Not a Trade-Off One of the most persistent misconceptions about ESG investing is the
The Power of Saying No in Investing: Why Discipline Protects Long-Term Wealth
The Power of Saying “No” in Investing When people think about successful investing, they often imagine bold decisions, brilliant stock picks, or extraordinary market timing. The narrative surrounding financial success frequently celebrates the investments that delivered exceptional returns. Yet one of the most powerful forces behind long-term wealth creation is rarely discussed. Great investing is not only about what you buy. It is equally about what you refuse. In professional portfolio management, some of the most valuable decisions are invisible. They are the investments that never enter the portfolio, the opportunities that appear attractive but are ultimately declined, and the trends that are deliberately ignored. Over the years working with international investors and families managing significant capital, many of the best outcomes for clients came from opportunities we chose not to pursue. Products with hidden risks. Strategies that promised returns that seemed too good to be sustainable. Complex financial structures that did not align with the investor’s long-term goals. Learning when to say “no” is one of the most important disciplines in investing. The Illusion of Opportunity Financial markets continuously produce new opportunities. Every year brings innovative investment products, emerging asset classes, and new market narratives. Some of these innovations genuinely improve portfolio construction and open valuable avenues for diversification. However, many others are designed primarily to attract attention rather than to generate sustainable value for investors. Financial marketing often emphasizes potential returns while minimizing discussion of risk. Promotional materials may highlight exceptional past performance, complex strategies, or technological sophistication. For investors navigating this landscape, distinguishing genuine opportunity from excessive risk becomes increasingly difficult. This is where disciplined decision-making becomes essential. Why Saying “No” Is Hard Rejecting an investment opportunity is rarely easy. Humans are naturally drawn toward potential gains. When presented with an attractive investment narrative, the fear of missing out can influence decision-making. This psychological pressure is amplified in environments where markets appear to be moving rapidly and others seem to be profiting. Social influence also plays a role. When a particular asset class or investment strategy becomes popular, declining participation can feel counterintuitive. However, successful investors understand that popularity and suitability are not the same. An investment may generate strong returns for some participants while being completely inappropriate for others. Experience as a Filter The ability to say “no” requires experience. Professional investors learn to evaluate opportunities through multiple lenses: risk exposure, structural complexity, liquidity conditions, and alignment with long-term portfolio objectives. Experience allows investors to recognize patterns that may not be immediately obvious. For example, products that promise unusually high returns often rely on leverage, illiquid assets, or hidden risk structures. Similarly, strategies built around complex derivatives or opaque financial engineering may introduce risks that are difficult for clients to fully understand. In these situations, declining participation is not a missed opportunity. It is responsible risk management. The Role of Independence Another critical factor in disciplined investment selection is independence. Advisors and portfolio managers must be free to evaluate opportunities objectively rather than being influenced by product distribution incentives or short-term performance pressures. Independent advice allows investment professionals to prioritize the long-term interests of clients rather than the immediate appeal of a new product or market trend. This independence creates an environment where saying “no” becomes a strategic decision rather than a commercial constraint. Protecting the Investor Journey At Income Capital Management, the central philosophy guiding portfolio construction is simple: we do not chase trends, we protect journeys. Each investor has a unique financial story. Their capital represents years of work, entrepreneurial success, or generational wealth that must be preserved and grown responsibly. Investment strategies should support this journey rather than expose it to unnecessary volatility. This means carefully evaluating whether each potential investment contributes to long-term objectives such as wealth preservation, income generation, or sustainable growth. If an opportunity does not align with these objectives, declining it becomes the most responsible decision. The Importance of Risk Awareness Risk awareness is at the core of disciplined investing. Every investment carries some level of risk, but not all risks are equally transparent. Some risks are obvious, such as market volatility, while others remain hidden within complex financial structures. Professional portfolio management involves identifying these hidden risks before they become problems. This may include evaluating liquidity constraints, understanding counterparty exposure, or analyzing how an investment behaves during economic downturns. When these risks outweigh the potential benefits, declining the opportunity protects the portfolio from unnecessary exposure. The Long-Term Mindset One of the defining characteristics of successful investors is a long-term mindset. Markets fluctuate constantly. Short-term trends appear and disappear with remarkable speed. However, wealth creation typically occurs over decades rather than days. This perspective allows disciplined investors to remain patient. They understand that not every opportunity needs to be captured. Instead, the focus remains on selecting investments that support long-term stability and growth. By prioritizing long-term objectives, investors avoid the temptation to chase short-lived market excitement. Building a Portfolio Through Selectivity Constructing a resilient portfolio involves careful selectivity. Each asset must serve a clear purpose within the overall structure. Some investments provide growth potential, others generate income, and some act as protection during periods of market stress. For example, diversified portfolios may include components such as: Global equity exposure for long-term growth Real estate investments providing stable income Currency strategies offering diversification Physical assets such as gold acting as protection By carefully selecting assets that complement one another, portfolios become more balanced and resilient. Declining unsuitable opportunities ensures that this structure remains intact. Investor Protection as a Guiding Principle Ultimately, the discipline of saying “no” is rooted in investor protection. Financial markets will always offer new opportunities, and some of them will indeed prove successful. However, protecting capital requires recognizing that not every opportunity deserves participation. Professional ethics demand that advisors prioritize the well-being of clients above the excitement of market trends. This responsibility requires patience, independence, and the willingness to reject investments that do not meet strict criteria. When Uncertainty Is a Signal Investors occasionally find themselves
Inside Our Forex Fund: Discipline Over Speculation
Inside Our Forex Fund: Discipline Over Speculation The foreign exchange market is often misunderstood. For many observers, Forex trading is associated with speculation, high leverage, and short-term bets driven by market sentiment. Media coverage and retail trading platforms have reinforced this perception, presenting currency markets as environments where rapid gains and equally rapid losses dominate the narrative. However, this simplified view fails to capture how professional investors actually approach currency markets. In institutional portfolio management, Forex is not merely a speculative arena. Instead, it can become a powerful strategic tool for diversification, risk control, and portfolio efficiency. At Income Capital Management, our Forex Fund is designed around a fundamentally different philosophy. Rather than chasing volatility or reacting emotionally to short-term movements, the strategy focuses on discipline, risk management, and systematic decision-making. In this framework, currency markets are not a casino. They are a structured financial environment where disciplined strategies can create stable opportunities while supporting broader portfolio objectives. Why Forex Markets Matter in Global Portfolios The foreign exchange market is the largest and most liquid financial market in the world. Every day, trillions of dollars are exchanged between currencies as governments, corporations, financial institutions, and investors conduct international transactions. This massive scale creates a unique investment landscape. Unlike equity markets, which depend on corporate performance, or bond markets, which are tied closely to interest rates and credit conditions, currency markets are influenced by a complex combination of macroeconomic forces. Interest rate differentials, monetary policy decisions, economic growth expectations, geopolitical developments, and trade balances all contribute to currency movements. For global investors with exposure to multiple currencies such as the euro, US dollar, or other major international currencies, these fluctuations can have a meaningful impact on overall portfolio performance. Rather than ignoring currency risk, professional investors seek to manage it. Moving Beyond the Speculation Narrative The idea that Forex trading is inherently speculative often arises from the behavior of retail market participants. High leverage, emotional trading decisions, and a lack of structured risk management frequently result in unpredictable outcomes. Professional Forex strategies operate very differently. Institutional approaches prioritize discipline, risk limits, and systematic processes. The objective is not to predict every short-term market movement, but to capture opportunities while maintaining strict control over potential losses. This disciplined structure is what transforms Forex from speculation into a legitimate portfolio management tool. The Core Principles of a Disciplined Forex Strategy The Forex Fund at Income Capital Management operates according to several fundamental principles that guide every trading decision. These principles are designed to ensure that the strategy remains aligned with long-term portfolio stability rather than short-term speculation. The key elements include: Strict risk management frameworks Carefully calibrated position sizing Continuous monitoring of market exposure Drawdown control mechanisms Scenario-based portfolio analysis Each of these components plays a specific role in maintaining the overall stability of the strategy. Position Sizing: Controlling Exposure Position sizing is one of the most important elements of professional trading. Rather than placing large bets on individual market views, disciplined Forex strategies distribute exposure across multiple positions with carefully calculated size limits. This approach ensures that no single trade can significantly damage portfolio performance. Even when market conditions become volatile, controlled position sizing allows the strategy to remain stable and resilient. Drawdown Control and Capital Preservation Another critical element of institutional trading is drawdown control. Every investment strategy will experience periods of underperformance. Markets move unpredictably, and even well-structured strategies cannot avoid temporary losses. However, the key to long-term success lies in limiting those losses. Drawdown control mechanisms establish predefined thresholds that restrict how much capital can be exposed to risk at any given time. When these thresholds are reached, exposure is reduced automatically. This systematic discipline helps ensure that temporary volatility does not evolve into structural portfolio damage. Continuous Monitoring of Currency Markets The global currency market operates twenty-four hours a day, five days a week. Economic events in one region can influence currency movements across the entire world. For this reason, professional Forex strategies rely on continuous monitoring. Market conditions are analyzed constantly, incorporating macroeconomic developments, central bank communications, and geopolitical changes. This ongoing evaluation allows portfolio managers to adapt positioning when necessary while maintaining strict adherence to risk frameworks. Scenario Analysis and Strategic Preparation Another essential component of disciplined Forex management is scenario analysis. Rather than focusing solely on the most likely market outcome, professional investors prepare portfolios for multiple potential scenarios. These scenarios may include changes in interest rate policies, shifts in global growth expectations, currency interventions by central banks, or geopolitical disruptions. By stress-testing portfolios against different environments, investors can better understand how currency exposures may behave under varying conditions. This preparation significantly reduces the risk of unexpected market shocks. Forex as a Diversification Tool One of the most valuable characteristics of Forex strategies is their potential diversification benefit. Currency markets often behave differently from traditional asset classes such as equities or real estate investments. Because currencies respond primarily to macroeconomic forces, they can provide portfolio exposure to different risk factors. This diversification effect can help smooth overall portfolio volatility. For investors with international financial exposure, currency management becomes an essential element of overall portfolio stability. Supporting International Investors Many global investors hold assets denominated in multiple currencies. European investors may hold US dollar investments, while American investors may maintain exposure to European or emerging market currencies. These currency exposures create additional layers of risk that must be managed carefully. Our Forex Fund helps address this challenge by providing a structured approach to currency management. By actively managing currency exposure, investors can reduce volatility while maintaining access to international investment opportunities. From Volatility to Opportunity Currency fluctuations often create uncertainty for investors. Rapid movements in exchange rates can influence international investment returns and introduce unexpected volatility. However, when approached with discipline and professional risk management, currency volatility can also create opportunity. A structured Forex strategy can convert market fluctuations into potential return sources while maintaining strict control over risk exposure. The Importance of Discipline in
How to Turn Market Noise into Actionable Investment Signals
How I Turn Market Noise into Actionable Signals Modern investors live in an era of unprecedented information abundance. Financial news travels instantly across global networks, analysts publish opinions around the clock, and social media constantly amplifies market commentary. Every day, investors are exposed to thousands of headlines, forecasts, predictions, and so-called “hot takes” about financial markets. At first glance, this may appear beneficial. After all, access to information has historically been considered an advantage in investing. However, the reality is more complex. The modern challenge is not the scarcity of information, but the overwhelming volume of it. For many investors, the constant flow of financial news becomes more confusing than helpful. Contradictory opinions appear within minutes of each other. One analyst predicts a recession while another forecasts rapid economic expansion. Headlines highlight market volatility while long-term data may tell a completely different story. In this environment, the real skill in investing is not simply collecting information. It is the ability to filter it. Transforming noise into clear, actionable signals is one of the most important tasks of professional portfolio management. The Problem with Financial News Overload Information overload affects both individual investors and institutional professionals. Markets react instantly to breaking news, central bank speeches, geopolitical developments, economic indicators, and corporate earnings announcements. Yet most of these events are short-term signals that can distract from long-term strategy. When investors attempt to react to every piece of news, they often end up making impulsive decisions that undermine disciplined portfolio construction. Markets move quickly, and reacting emotionally to daily headlines can result in unnecessary trading, increased transaction costs, and poor timing. This is why professional investors must build structured frameworks for interpreting information. The objective is not to follow every news cycle. The objective is to identify which signals genuinely matter. From Noise to Strategy The process of turning market noise into actionable investment signals begins with filtering. Not every headline deserves equal attention. Professional investment analysis relies on structured frameworks that prioritize data over opinion. At Income Capital Management, the decision-making process combines multiple layers of analysis. Each layer helps transform fragmented information into a coherent strategy. These layers include: Macroeconomic indicators Sector and market trends Quantitative models ESG and structural data Risk management metrics By integrating these perspectives, investors can move beyond short-term market commentary and focus instead on meaningful signals. Macroeconomic Indicators as Strategic Anchors Macroeconomic data forms the foundation of long-term investment decisions. Indicators such as inflation rates, interest rate expectations, employment data, and economic growth projections provide essential context for market movements. For example, central bank policies often drive major asset class performance. When inflation rises above central bank targets, monetary authorities typically tighten policy by raising interest rates. Higher interest rates can influence currency valuations, credit spreads, and equity market dynamics. Similarly, economic slowdown signals can affect corporate earnings expectations and investor risk appetite. Understanding these macroeconomic dynamics allows investors to interpret financial news within a broader framework. Rather than reacting to isolated headlines, macro indicators help investors identify structural trends shaping market behavior. Sector Trends and Structural Shifts Beyond macroeconomic indicators, sector-level trends play an important role in identifying investment opportunities. Global economies continuously evolve as technology, demographics, and policy changes reshape industries. For instance, renewable energy investments have gained momentum due to climate policies and technological advances. Meanwhile, artificial intelligence and digital infrastructure have created new opportunities within technology and data sectors. By tracking sector-level developments, investors can position portfolios to benefit from structural economic changes rather than temporary market sentiment. This strategic perspective helps investors capture long-term growth opportunities while maintaining diversification. The Role of Quantitative Models Quantitative analysis adds another layer of discipline to investment decision-making. Data-driven models help remove emotional bias and provide objective signals for portfolio adjustments. Quantitative frameworks can analyze market volatility, momentum trends, correlation structures, and statistical relationships between asset classes. For example, in Forex trading strategies, quantitative models may evaluate currency momentum, macroeconomic differentials, and volatility patterns. These models help determine when to rebalance positions, adjust exposure, or reduce risk. While quantitative models do not eliminate uncertainty, they provide structured guidance that improves consistency in portfolio management. Integrating ESG Data into Investment Analysis Environmental, social, and governance (ESG) data has become increasingly relevant in global investment strategies. ESG indicators provide insights into corporate governance quality, environmental sustainability practices, and long-term operational resilience. For institutional investors and wealth managers, ESG data can help identify companies and sectors that are better positioned for regulatory changes and evolving market expectations. Integrating ESG considerations into investment analysis allows portfolios to incorporate broader structural trends beyond traditional financial metrics. This perspective enhances risk assessment and supports long-term portfolio sustainability. Risk Management as a Central Discipline Transforming information into signals is only useful if it leads to effective risk management. Professional portfolio construction always prioritizes capital preservation alongside growth opportunities. Markets inevitably experience periods of volatility. Economic cycles fluctuate, geopolitical tensions arise, and unexpected events can influence asset prices. Risk management frameworks help ensure that portfolios remain resilient across different scenarios. This may involve diversification across asset classes such as currencies, real estate investments, credit instruments, equities, and physical assets like gold. By maintaining balanced exposure, portfolios can withstand short-term disruptions while remaining positioned for long-term growth. Applying Signals Across Multiple Asset Classes Once filtered signals are identified, the next step involves translating them into portfolio actions. These actions may include: Rebalancing asset allocations Reducing exposure to overvalued sectors Increasing allocation to defensive assets Capturing opportunities in currency markets Adjusting credit or real asset exposure Each portfolio decision must align with the investor’s long-term objectives and risk tolerance. Short-term signals should support, not override, strategic portfolio design. Helping Investors Navigate Information Overload Many investors feel overwhelmed by the constant flow of financial news. This is understandable. The modern information environment rewards speed and attention-grabbing headlines rather than thoughtful analysis. However, successful investing rarely depends on reacting to every piece of news. Instead, it requires patience, discipline, and structured interpretation of information. With the
What Clients Really Ask About Investing: Trust, Clarity and Financial Decisions
What Clients Really Ask About Investing After many years working with international investors, entrepreneurs, and families managing significant financial assets, one observation becomes very clear: the questions clients ask are rarely about financial products themselves. Most people assume that conversations with investment professionals revolve around technical topics such as portfolio allocation, specific funds, derivatives, or market forecasts. In reality, the questions that truly matter are much deeper and more personal. Clients are not primarily concerned with the mechanics of a Forex strategy, the duration of a bond portfolio, or the precise structure of a real estate fund. Instead, their questions revolve around three fundamental themes: trust, clarity, and outcomes. Behind every portfolio discussion lies a much more important conversation about financial security, life goals, and long-term peace of mind. After working with investors across Europe, the United States, and the Middle East through Income Capital Management, certain questions appear again and again. They reflect universal concerns that transcend markets, asset classes, and economic cycles. The Real Questions Behind Investment Decisions When clients begin a conversation about investing, they rarely start with technical language. Instead, they ask questions like: “Will I be able to retire comfortably?” “Can I protect my family if markets turn?” “Am I making the right financial choices today?” These questions may appear simple, but they carry enormous weight. They reflect the responsibility investors feel toward their families, their future lifestyle, and the legacy they hope to build. Investing, at its core, is not about beating an index or chasing the highest possible returns. It is about designing a financial strategy that allows individuals to live the lives they want while maintaining confidence that their capital is being managed responsibly. This is why the role of a financial advisor is far broader than simply selecting investments. It involves translating complexity into clarity. Trust: The Foundation of Every Investment Relationship Trust is the single most important element in wealth management. Markets fluctuate, strategies evolve, and economic environments change. However, trust between an investor and their advisor must remain constant. Without it, even the most sophisticated portfolio structure becomes meaningless. Investors trust advisors with more than just capital. They entrust them with years of hard work, entrepreneurial success, family inheritance, and future financial stability. This responsibility requires transparency, discipline, and intellectual honesty. At Income Capital Management, building trust means maintaining clear communication about both opportunities and risks. It means avoiding unrealistic promises and focusing instead on structured, long-term strategies. Clients should always understand not only what they are investing in, but why. Clarity in a Complex Financial World The modern financial landscape is more complex than ever. Investors are confronted daily with an overwhelming flow of information: market commentary, social media speculation, economic predictions, and endless financial products promising superior returns. While access to information has increased dramatically, true clarity has become more difficult to achieve. Many investors feel overwhelmed by financial jargon and technical terminology. They encounter discussions about derivatives, volatility structures, algorithmic strategies, or macroeconomic hedging mechanisms that seem unnecessarily complicated. In many cases, complexity is mistaken for sophistication. However, successful investing does not require confusion. It requires understanding. The role of a professional advisor is therefore to simplify financial decision-making without oversimplifying the underlying risks. Clarity means explaining how each component of a portfolio contributes to an investor’s long-term goals. Translating Financial Tools into Real Decisions At Income Capital Management, we work with a diversified framework that includes several asset classes and strategies: Forex investment strategies Real estate income opportunities High yield and global growth allocations Physical gold holdings Non-discretionary advisory portfolio structures Each of these tools serves a specific purpose within a broader portfolio architecture. Forex strategies can provide return potential through disciplined trading models and systematic execution. Real estate investments often provide stability and recurring income, acting as a foundation within the portfolio. High yield and global growth strategies introduce exposure to broader economic expansion and credit opportunities. Physical gold adds an element of tangible asset protection and often performs differently from traditional financial markets during periods of macroeconomic stress. However, none of these strategies are meaningful if they remain abstract financial concepts. The real objective is to translate them into clear, practical decisions that investors understand and feel comfortable implementing. The Emotional Dimension of Investing Financial markets are often described in mathematical or economic terms. Yet the emotional dimension of investing is equally important. Fear, uncertainty, and overconfidence can influence investor behavior far more than data or analysis. During periods of market volatility, even experienced investors can feel tempted to abandon long-term strategies in favor of reactive decisions. This is why disciplined portfolio construction is essential. A well-structured portfolio does not attempt to predict every market movement. Instead, it prepares for a wide range of possible outcomes. Investors who understand the role of each asset class within their portfolio are less likely to make emotional decisions during periods of stress. Confidence in the strategy reduces the temptation to react impulsively. Outcomes Matter More Than Products Ultimately, investors do not measure success based on how sophisticated their portfolios appear. They measure success through outcomes. Can the portfolio support long-term financial independence? Does it provide sufficient protection during economic downturns? Is it structured to generate consistent growth while controlling risk? These questions are far more meaningful than discussions about specific financial instruments. For this reason, the conversation with clients always returns to the same central theme: aligning investment strategy with life objectives. The Role of the Advisor: Partner, Not Provider The relationship between an investor and an advisor should not resemble a simple commercial transaction. An advisor should not act merely as a provider of financial products. Instead, the advisor should serve as a long-term partner in financial decision-making. This partnership involves ongoing dialogue, periodic portfolio review, and continuous adaptation to changing economic conditions. Markets evolve, regulations change, and personal circumstances develop over time. A portfolio strategy must evolve accordingly. By maintaining a disciplined advisory approach, investors gain the benefit of professional insight without surrendering
Why Diversification Still Wins in 2026
Why Diversification Still Wins in 2026 Financial markets evolve constantly. Headlines change daily. New technologies emerge. Geopolitical tensions reshape trade routes and capital flows. Monetary policies shift direction faster than many investors expect. Yet amid this constant change, one principle has demonstrated remarkable durability across centuries of financial history: diversification. Diversification is not simply an academic theory or a portfolio construction buzzword. It is one of the most powerful risk management tools available to investors seeking to preserve and grow capital over long horizons. In 2026, the argument for diversification is stronger than ever. The Changing Nature of Market Risk The global investment landscape today is characterized by multiple overlapping sources of uncertainty: Interest rate policy divergence across major economies Persistent geopolitical tension in strategic regions Supply chain restructuring and trade fragmentation Technological disruption across industries Currency volatility linked to capital flows In such an environment, concentrated portfolios become increasingly vulnerable to unexpected shocks. Diversification acts as a structural defense mechanism against these uncertainties. Diversification Is Not About Owning “Many Assets” A common misunderstanding is that diversification simply means holding a large number of securities. In reality, true diversification is achieved by combining assets that respond differently to economic conditions. The objective is not quantity, but complementary behavior. Assets must react differently to: Inflation shocks Interest rate changes Economic expansion or contraction Currency movements Geopolitical instability A portfolio containing many correlated assets is not diversified — it is merely crowded. The Multi-Asset Framework At Income Capital Management, diversification is implemented through a structured multi-asset approach that integrates several complementary investment engines. Each asset class fulfills a specific role within the overall portfolio architecture. Forex Strategies Currency markets provide flexibility and tactical adaptability in response to macroeconomic shifts. Central bank policy divergence, trade balances and capital flows create opportunities for disciplined Forex strategies. In diversified portfolios, currency exposure can act as both a return generator and a risk mitigation tool. Real Estate Exposure Real estate plays a stabilizing role within portfolios. Unlike liquid financial instruments, property assets often exhibit slower price adjustments and provide income through rental flows. This combination offers partial insulation from short-term market volatility. Within a diversified allocation, real estate contributes income stability and inflation sensitivity. Physical Gold Allocation Gold has historically functioned as a store of value during periods of financial stress, currency instability and geopolitical tension. Physical gold holdings can act as a structural hedge when confidence in fiat currencies weakens or when financial markets experience sudden volatility spikes. Its role is not aggressive growth, but protection and balance. Global Growth Investments Equity exposure to global growth sectors provides participation in long-term economic expansion and technological innovation. High-quality companies with durable competitive advantages can generate compounding returns across cycles. Within the diversified structure, growth assets provide capital appreciation potential. High Yield Income Strategies Selective exposure to credit markets can generate attractive income streams when carefully managed. High yield allocations must be calibrated to avoid excessive credit risk, but when integrated appropriately they contribute yield and diversification relative to equity markets. The Role of Risk Management Diversification alone is insufficient without disciplined risk management. Asset allocation must be continuously monitored to ensure that correlations remain balanced and that exposure does not become unintentionally concentrated. Risk management includes: Periodic portfolio rebalancing Volatility monitoring Scenario analysis and stress testing Liquidity assessment Through these mechanisms, diversification remains effective even as market conditions evolve. Diversification Across Time Horizons Investors often evaluate diversification through the lens of short-term performance. However, diversification demonstrates its greatest value over extended time horizons. Different asset classes outperform during different phases of the economic cycle. By maintaining exposure across multiple drivers of return, diversified portfolios reduce dependence on any single market environment. Behavioral Benefits of Diversification Diversification also provides psychological advantages. Investors who hold concentrated portfolios are more vulnerable to emotional reactions during volatility. Large fluctuations in a single asset can create anxiety and lead to impulsive decisions. Diversified portfolios tend to exhibit smoother return profiles, which helps investors maintain discipline. Global Investors Require Global Diversification Income Capital Management serves investors across Europe, the United States and the United Arab Emirates. These clients operate within different currencies, regulatory frameworks and economic environments. Global diversification ensures that portfolios remain resilient across regional economic shifts. Currency diversification, geographic exposure and sector allocation all contribute to reducing concentration risk. Preparing Capital for the Next Decade Investment strategy should not be built around daily headlines. It should be designed for long-term durability. When investors ask how to prepare their capital for the next decade rather than the next news cycle, diversification becomes the logical starting point. The goal is not to predict which asset will perform best tomorrow. The goal is to construct a system capable of adapting to whatever tomorrow brings. Diversification as a Working Method At Income Capital Management, diversification is not an abstract principle. It is a working method embedded in portfolio design, risk monitoring and advisory relationships. By combining Forex strategies, Real Estate exposure, Physical Gold holdings, Global Growth investments and High Yield income streams, portfolios become structurally balanced across multiple economic scenarios. Diversification transforms uncertainty from a threat into a manageable variable. Conclusion Markets will continue to evolve. New risks will emerge. Unexpected opportunities will appear. But the principle of diversification remains remarkably resilient. By spreading exposure across complementary asset classes and maintaining disciplined risk management, investors can build portfolios designed not only to survive volatility, but to grow steadily through it. In a complex financial world, diversification remains one of the simplest — and most powerful — strategies available. LinkedIn Post: https://www.linkedin.com/feed/update/urn:li:activity:7434160637879955456
March 2026 Update | Discipline in a Complex Environment
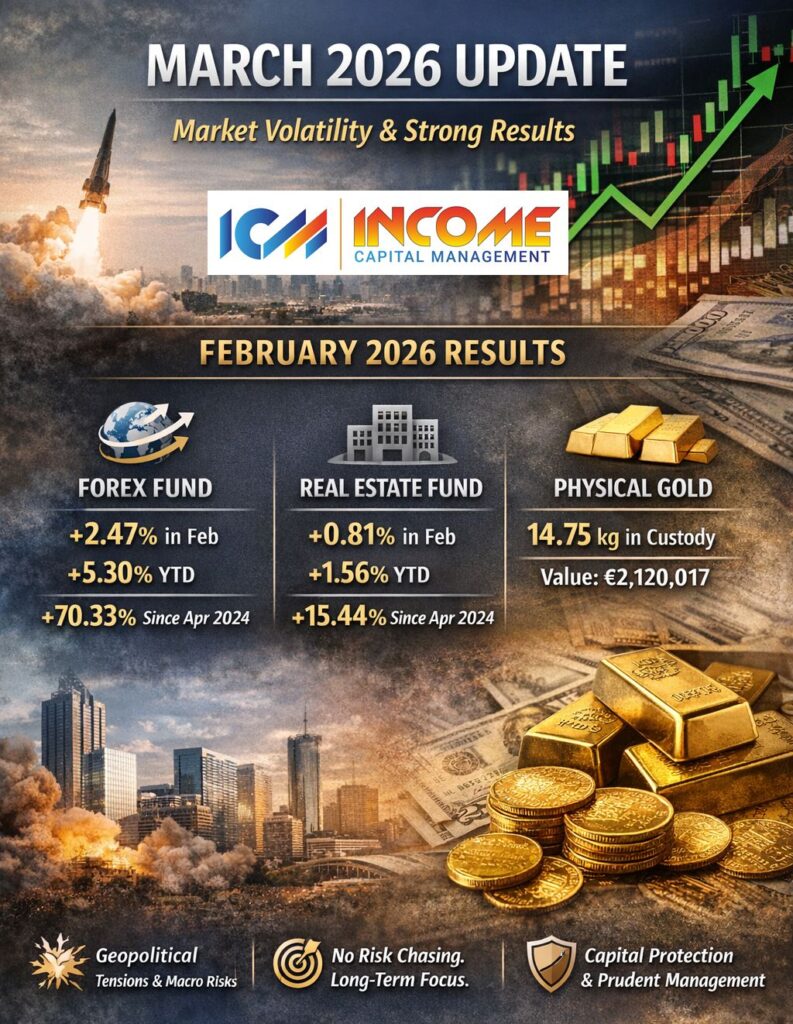
March 2026 Update | Discipline in a Complex Environment The first months of 2026 confirmed what experienced investors already understand: volatility does not disappear — it transforms. Markets remain highly sensitive to monetary policy signals, macroeconomic data releases and geopolitical developments. The ongoing conflict in the Middle East and renewed tensions involving the United States, Israel and Iran have reintroduced structural uncertainty into global capital markets. Interest rate expectations continue to fluctuate. Inflation remains a debated variable. Liquidity conditions are uneven across regions. Currency volatility is elevated. In this context, active and prudent portfolio management remains essential. Macro Environment: Fragility Beneath Stability While headline equity indices have shown resilience in early 2026, underlying cross-asset dispersion tells a more nuanced story. Currency markets are reacting sharply to central bank tone shifts. Energy and commodity pricing reflects geopolitical risk premium. Bond markets are recalibrating inflation expectations. Emerging markets face capital flow volatility. Volatility has not disappeared. It has become selective. In such an environment, discipline becomes more valuable than prediction. Income Capital Management – February 2026 Results FOREX FUND February 2026: +2.47% 2026 YTD: +5.30% Since April 2024: +70.33% The Forex strategy continues to benefit from structured positioning in high-volatility currency environments. Central bank divergence remains a core driver. Tactical adjustments were implemented in response to policy signals and risk sentiment oscillations. Risk exposure was actively calibrated to avoid excessive directional bias during geopolitical escalation phases. The strategy remains rule-based, disciplined and aligned with predefined risk thresholds. REAL ESTATE FUND February 2026: +0.81% 2026 YTD: +1.56% Since April 2024: +15.44% The Real Estate Fund continues to deliver stable income characteristics within a diversified allocation framework. In a context where financing costs remain elevated compared to previous years, careful asset selection and tenant quality analysis remain fundamental. The role of real estate within the broader portfolio is not high acceleration. It is income stability and partial inflation mitigation. PHYSICAL GOLD 1.30 kg purchased in February Total custody: 14.75 kg Market value (28/02/2026): €2,120,017 Gold continues to function as a structural hedge within our allocation model. Heightened geopolitical tensions, combined with uncertainty around real interest rate trajectories, support ongoing demand for physical allocation. Our approach remains physical custody based, transparent and integrated into overall portfolio design — not speculative. No Structural Change in Philosophy In volatile environments, investors often seek dramatic tactical shifts. Our framework remains unchanged: No short-term speculation No risk chasing Structured exposure aligned with macro conditions Focus on capital protection and long-term consistency Consistency is not rigidity. It is disciplined adaptability. Active Management in 2026: Why It Matters Passive allocation assumes stable structural regimes. The current environment is defined by: Geopolitical fragmentation Inflation regime uncertainty Currency realignment risks Liquidity divergence between regions In such an environment, active oversight enhances: Risk calibration Exposure control Correlation monitoring Scenario responsiveness Capital Protection as Strategic Priority Long-term wealth accumulation depends on minimizing severe drawdowns. A 30% loss requires a 43% recovery. A 40% loss requires a 67% recovery. Capital preservation discipline reduces recovery burden. Our allocation decisions remain aligned with this principle. Looking Ahead As we move deeper into 2026, three variables remain central: Monetary policy trajectory Geopolitical escalation or stabilization Global growth sustainability We continue to monitor macro data and liquidity indicators closely, maintaining flexibility while preserving structural discipline. In uncertain environments, structure, discipline and risk control make the difference. Full monthly report available here: https://lnkd.in/d72udys4 LinkedIn Post: https://www.linkedin.com/posts/paolovolpicelli_discipline-complex-markets-activity-7434212609194737665-9dDW

